Claims-Made vs Occurrence Malpractice Insurance: Physician Guide
Claims-Made vs Occurrence Malpractice Insurance: What Physicians Need to Know
One of the most important decisions in medical malpractice insurance is not simply which carrier to choose.
It is understanding how the policy responds to claims.
Two common structures are:
claims-made coverage and occurrence coverage.
The distinction can have significant implications when physicians change employers, switch carriers, retire or sell a practice.
👉 Review Your Malpractice Coverage Profile
What Is Claims-Made Malpractice Insurance?
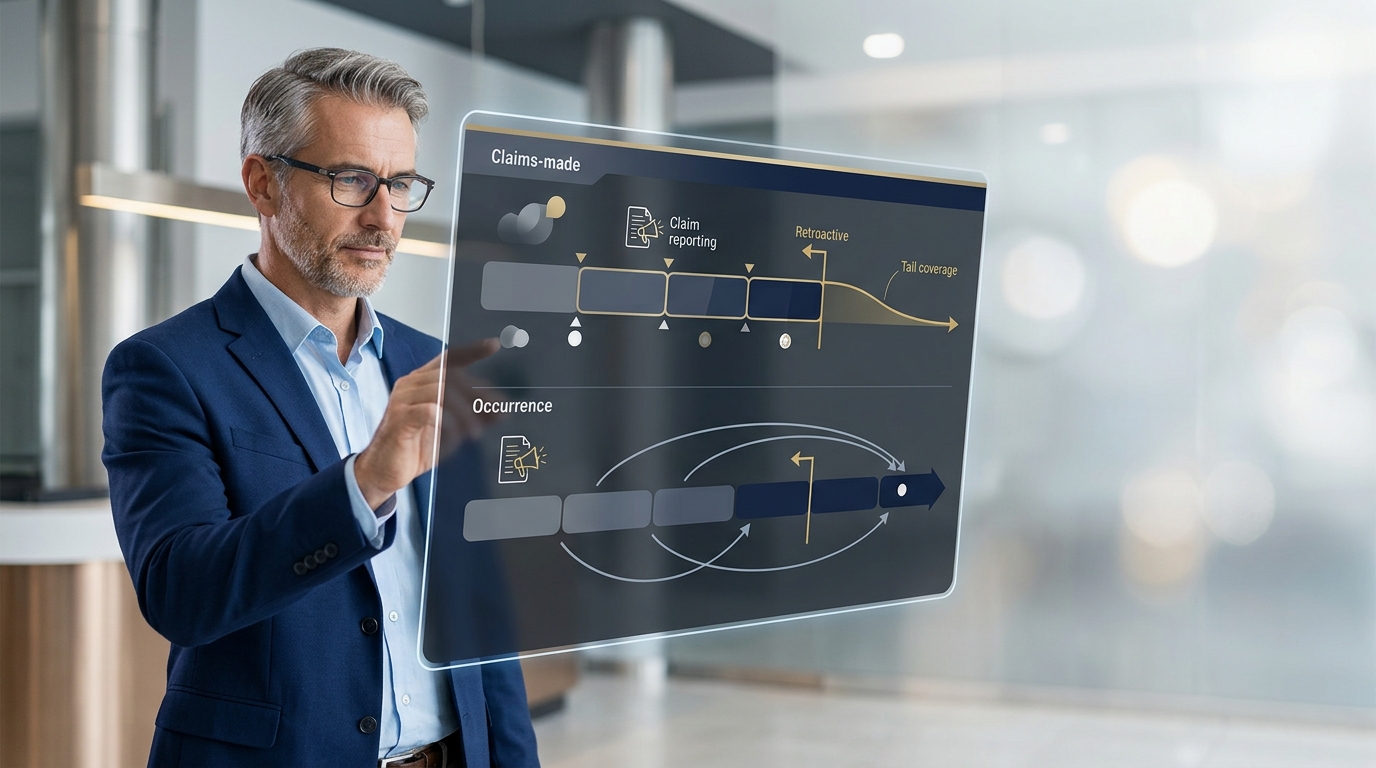
A claims-made policy generally requires a claim to be reported while the applicable policy is in force, subject to the policy’s specific terms and retroactive date.
The retroactive date is especially important.
It generally identifies how far back covered professional services may extend under the policy.
Continuous prior-acts coverage can therefore become an important consideration when moving between carriers.
What Is Occurrence Malpractice Insurance?
Occurrence coverage generally responds according to when the covered incident occurred.
If the incident occurred during the policy period, a later claim may still fall under that policy, subject to the policy’s terms.
This is one reason occurrence policies generally do not create the same tail coverage issue when the policy terminates.
What Is Tail Coverage?
Tail coverage is commonly called an extended reporting period endorsement.
It may allow certain claims arising from covered services performed before termination of a claims-made policy to be reported after that policy has ended.
Tail coverage can become relevant when a physician:
- changes jobs
- retires
- changes carriers
- sells a practice
- moves
- restructures coverage
What Is Nose or Prior-Acts Coverage?
Instead of purchasing tail coverage from the previous insurer, a physician may sometimes obtain prior-acts coverage from the new insurer.
This is commonly called nose coverage.
Whether it is available depends on carrier underwriting and the physician’s circumstances.
Which Type Is Better?
Neither structure is automatically best for every physician.
The appropriate choice depends upon factors such as:
- total long-term cost
- employer obligations
- career mobility
- tail provisions
- retroactive date
- carrier terms
- specialty
- future retirement plans
One of the biggest mistakes physicians make is comparing only the first-year premium without evaluating what happens when coverage ends.
Questions to Ask Before Switching Malpractice Policies
Before changing carriers or employers, determine:
Who is responsible for tail coverage?
What is your retroactive date?
Will the new policy provide prior-acts coverage?
Are policy limits changing?
Could there be a gap in coverage?
Are there contractual tail obligations in your employment agreement?
Why This Matters During Underwriting
A coverage gap can affect more than claims protection.
It may also complicate future underwriting.
Carriers frequently review continuity of coverage, prior policies and loss history when evaluating a physician.
Assess Your Current Coverage Structure
If you’re considering new malpractice coverage, your policy structure should be reviewed alongside specialty, state, claims history and limits.
👉 Start the Free Physician Underwriting Assessment
Bottom Line
Claims-made and occurrence malpractice insurance can both provide important protection, but they function differently.
For physicians with claims-made coverage, pay particular attention to:
retroactive dates, prior acts and tail obligations.
Do not make a coverage change based solely on the annual premium.