The Cheaper Malpractice Quote Might Be the More Expensive One
Would you take the quote that’s $6,000 cheaper?
Two malpractice quotes. Same stated limits. The cheaper one writes a new retroactive date. Now imagine a patient you treated three years ago makes a claim after you switch. Which policy are you counting on?
By Samuel Bennett, licensed insurance agent · November 2026
Same limits. Different years of care.
Imagine you own an independent practice. Your current claims-made policy goes back to January 1, 2020. Both new quotes would start January 1, 2027. Nothing has been bound, and you haven’t secured tail. Which would you pursue?
$18,500
- Stated limits
- $1M / $3M
- Retroactive date
- Jan. 1, 2027
- Defense costs
- Inside limits
$24,500
- Stated limits
- $1M / $3M
- Retroactive date
- Jan. 1, 2020
- Defense costs
- Outside limits, subject to policy terms
Read the example and the math
In this fictional scenario, the patient was treated in 2023 and first made a claim after the switch. Quote A’s 2027 retroactive date puts that care before the new policy’s date. Quote B’s 2020 date keeps that year in play, but it does not promise coverage. The policy’s reporting rules, exclusions, insured parties, and covered services still apply.
Now suppose the old carrier offers applicable tail for a one-time $9,000. Paying for that tail yourself would put Quote A at $27,500 in illustrated first-year cost, or $3,000 more than Quote B in this example. That assumes Quote B needs no separately purchased tail for the switch. It is not a claim that Quote A costs more every year or that the two coverage arrangements are equivalent.
The cheaper quote can still be the right one.
Nearly 40% of the premiums tracked in the 2025 survey rose, according to the AMA’s 2026 analysis. That’s a good reason to shop your renewal. It’s also a good reason to ask what changed when a replacement quote comes back substantially lower. The premium doesn’t tell you whether the new carrier will pick up your prior work or whether you’ll need to pay to extend the time to report claims under the old policy.
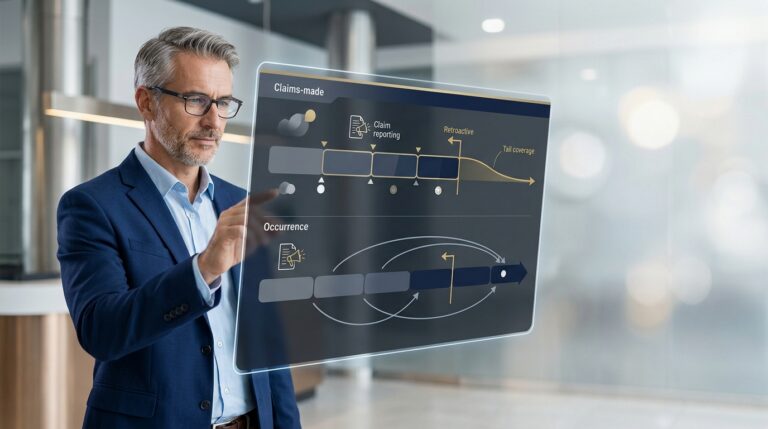
With a claims-made policy, the retroactive date is generally the earliest date of care the policy can consider, subject to its other terms. Tail generally extends the time to report eligible claims arising from care during the covered period under the old policy. It does not cover new work after that policy ends. Prior-acts coverage can bring eligible earlier work onto the new policy. A matching date matters, but so do the names, entities, locations, services, and exclusions that go with it.
Look at defense costs separately. If covered defense costs are inside the limits, they can reduce the amount left to pay a settlement or judgment. “Outside limits” doesn’t automatically mean unlimited defense. Ask for the wording and any separate cap.
“If a patient I treated in 2023 makes a claim after this switch, which policy should I report it to? Please show me the retroactive date, who is insured, and the wording that applies to that work.”
Malpractice renewal quote checker
Enter the full annual premiums, then add what your practice would actually pay for any tail needed because of the switch. Use the coverage notes to see what still needs confirmation.
No login, uploads, or patient information. The checker does not submit or store your entries. It compares first-year cash cost only and does not determine coverage.
If the calculator controls don’t appear, compare each annual premium plus any one-time tail cost your practice would pay. Keep an unknown tail cost out of the total until you get it in writing.
Three questions for your renewal call
- Who covers my prior work? Compare the current declarations with the proposed declarations and endorsements. Confirm the retroactive date and the physicians, practice entities, procedures, and locations covered. If using tail, confirm what it covers, how long it lasts, the purchase deadline, and who pays.
- What changed besides price? Compare per-claim and aggregate limits, deductibles, defense costs, and exclusions. If one quote is introductory or not yet at a mature claims-made rate, ask for the projected premium steps in writing.
- What should I report before the switch? If you have an open claim, a demand, or a known incident, review the current policy’s notice provisions and contact the appropriate carrier or broker promptly. Don’t assume a new policy or tail will automatically fix a late notice or pick up a known matter.
Switching after a non-renewal or with prior claims? Don’t cancel existing coverage based on a proposal. Confirm the replacement is bound and verify, in writing, how any prior work and reporting obligations are handled.
Have a quote in hand or a renewal coming up?
I’ll help you compare your current terms with the replacement quote and identify what still needs a written answer. That’s especially useful if you’re facing a non-renewal, have prior claims, or aren’t sure what will happen to your retroactive date.
Samuel Bennett · Licensed insurance agent · Island Insurance Group
sam@islandinsurancegroup.com · 954-804-8144