Medical Malpractice Insurance: What Physicians Should Review Before a Claim Happens
Many physicians look closely at their medical malpractice insurance at renewal.
Others do not examine the details until a claim or potential claim develops.
That can be a difficult time to discover how the policy actually works.
Medical malpractice insurance for physicians contains several provisions that can materially affect coverage. Understanding those provisions before a claim happens can make the insurance program easier to evaluate.
Know Whether the Policy Is Claims-Made or Occurrence
One of the first questions a physician should ask is whether the malpractice policy is written on a claims-made or occurrence basis.
With an occurrence policy, coverage is generally connected to when the covered incident occurred, subject to the policy terms.
With a claims-made policy, both the timing of the professional incident and the timing of the claim or reporting can be important.
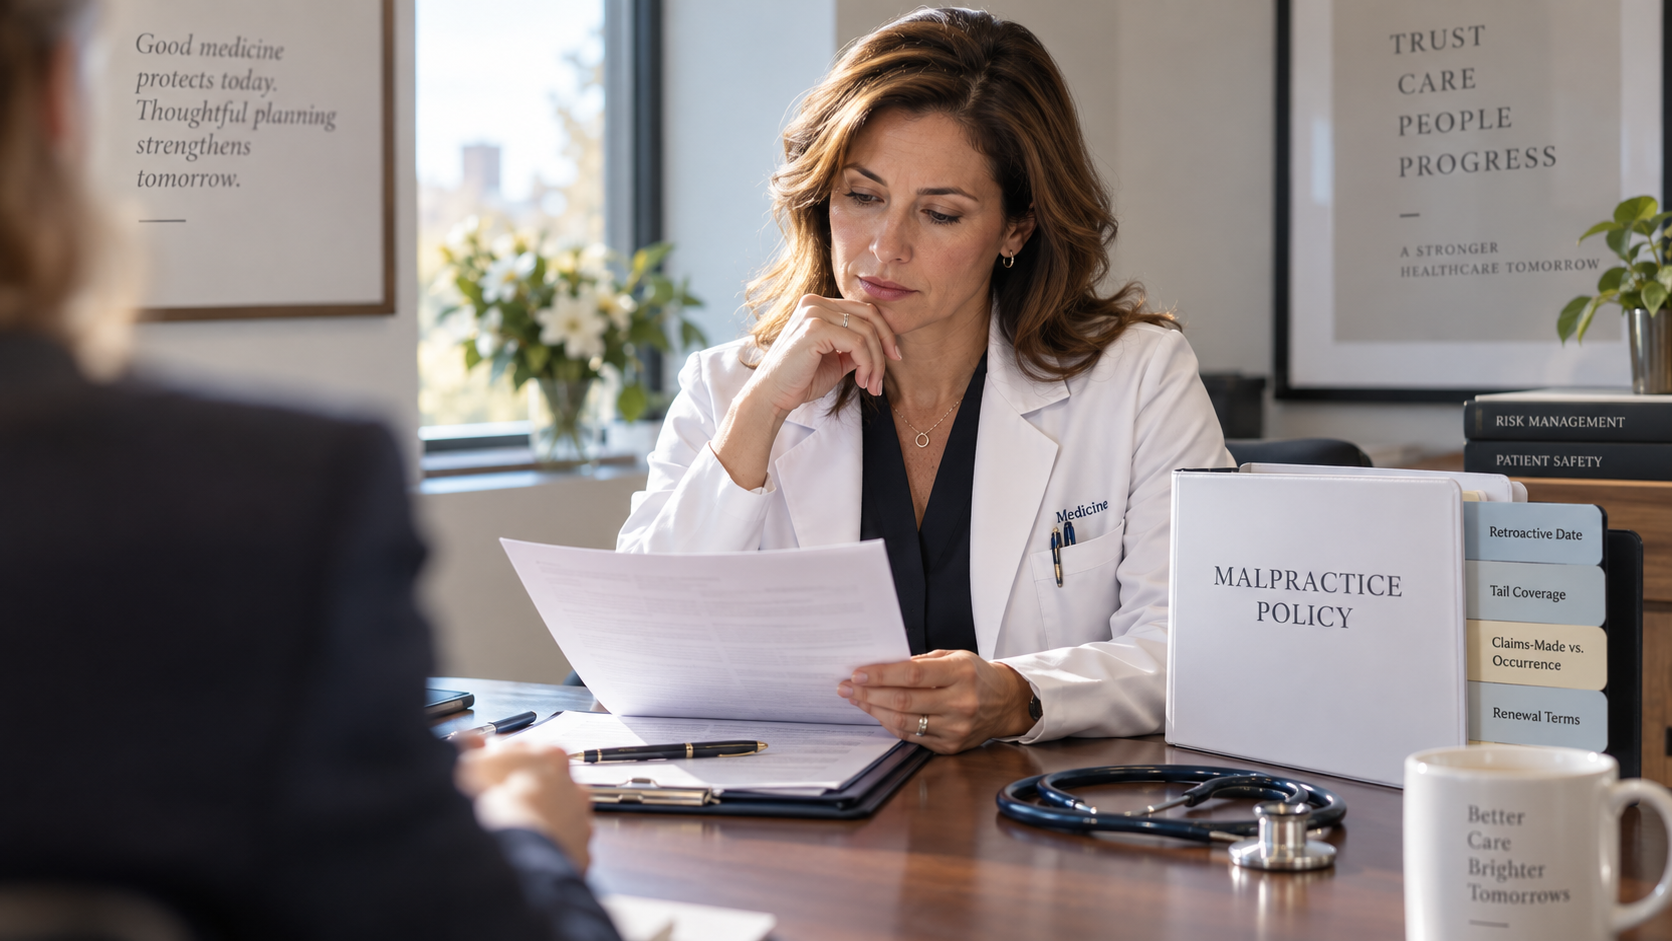
Claims-made coverage also introduces another critical concept: the retroactive date.
Understand Your Retroactive Date
The retroactive date may determine how far back prior professional services can qualify for coverage under a claims-made policy.
A physician changing carriers should pay close attention to whether the new policy maintains the appropriate retroactive date or provides prior-acts coverage.
Losing continuity can create a serious coverage issue.
A lower premium is not necessarily a better outcome if the replacement coverage changes important protections.
Understand Tail Coverage
Tail coverage, also called an extended reporting period, may become important when claims-made coverage ends.
This can happen when a physician:
- Retires
- Changes employers
- Changes insurance carriers
- Leaves private practice
- Moves into a different role
- Terminates a claims-made policy
The exact need for tail coverage depends on the circumstances and policy language.
Physicians should determine who is responsible for purchasing tail coverage before changing employment or insurance arrangements.
Review Policy Limits
Malpractice policies typically contain limits.
A physician should understand both the individual claim limit and any aggregate limit that may apply.
Different specialties and practice environments can involve different risk considerations.
Limits should be evaluated in the context of the physician’s specialty, location, contracts, practice structure, and other factors.
Review Defense Provisions
The defense of a malpractice claim can be a major part of the insurance response.
Physicians should understand whether defense expenses reduce the available policy limit or are handled separately.
Other questions can include:
- Who selects defense counsel?
- Does the insurer have the right to settle?
- Is physician consent required for settlement?
- Are there provisions affecting what happens if settlement is declined?
These provisions vary between policies.
Review Exclusions
Every insurance policy contains exclusions.
Physicians should review exclusions that could be relevant to their practice, especially if the scope of services has changed.
New procedures, telemedicine, aesthetic services, supervisory responsibilities, or ownership interests may change the risk profile.
The policy should reflect what the physician actually does.
Watch the Physician Risk Film
A malpractice claim is not the only event that can affect a medical practice.
Island Insurance Group created a short film exploring how malpractice exposure and cyber risk can intersect.
Watch the physician risk film.
Review Coverage Before Changing Carriers
Changing malpractice insurance should involve more than comparing premiums.
A physician should evaluate:
- Retroactive dates
- Prior-acts coverage
- Tail requirements
- Limits
- Deductibles
- Defense provisions
- Exclusions
- Carrier financial strength
- Claims handling
- Effective dates
A transition between policies should be coordinated carefully.
Additional physician insurance resources are available through Island Insurance Group and its Resources section.