1099 vs. W-2 for Physicians | Offer Calculator
Before You Say Yes · Island Insurance Group
Would you turn down an extra $50 an hour?
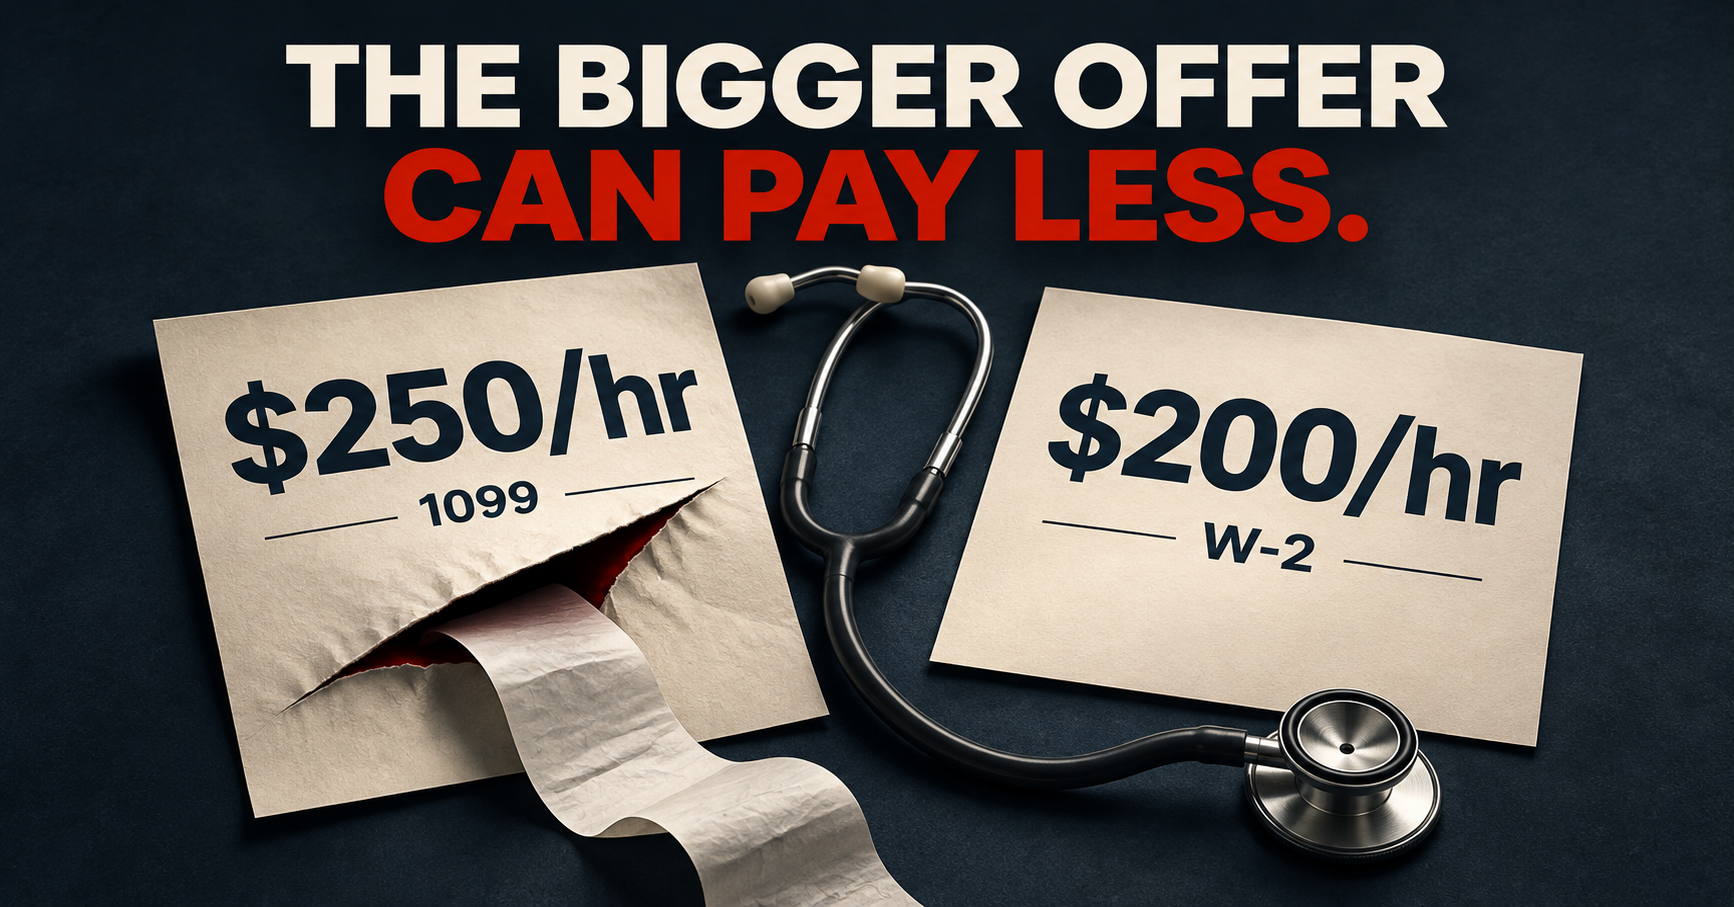
The recruiter offers you $250 an hour as a 1099 physician. Your other offer pays $200 an hour as a W-2 employee. In one fictional comparison, the lower rate comes out $18,000 ahead in annual pre-tax value. The difference is in the paid time off, benefits, and bills you’d pay yourself.
1099 vs. W-2 Physician Offer Calculator
Start with the fictional offers, then replace the numbers with yours. Dollar amounts are annual unless labeled hourly. Use zero only if an item doesn’t apply. If you don’t know a cost, run a low and a high estimate.
If the calculator doesn’t appear, use the worked example immediately below.
Comparison results
W-2 estimated value
1099 estimated value
This comparison estimates pre-tax offer value, not take-home pay, worker classification, or insurance coverage.
No email address or document upload is needed. The calculator itself does not send or store your entries.
How a $250-an-hour offer can be worth less than $200
Both fictional physicians work 46 weeks at 40 paid clinical hours per working week. The W-2 offer pays for 50 weeks total, including four weeks of paid time off. The 1099 offer pays only for hours worked.
- W-2: $200 × 40 × 50 = $400,000 in wages. Add $30,000 in employer-funded benefits the physician values. With no out-of-pocket costs in this example, the result is $430,000 in pre-tax value.
- 1099: $250 × 40 × 46 = $460,000 in billings. Subtract $18,000 in unreimbursed travel, $22,000 in malpractice premiums, and an $8,000 annual reserve toward a hypothetical tail expense. That leaves $412,000 in pre-tax value.
At the same hours and costs, the 1099 offer would need to pay at least $259.79 per billable hour to match the modeled W-2 value. These figures illustrate the math. They are not market rates, and different benefits, reimbursement, or insurance terms can flip the result.
What the comparison counts and what it leaves out
W-2 value is base cash pay plus additional cash pay and employer-funded benefits you value, minus unreimbursed work costs. If the offer is salaried, divide the annual base salary by the modeled paid hours to get the hourly equivalent to enter. That is a way to enter the salary, not an assertion that your employer pays you hourly.
1099 value is hourly pay times billable hours, plus additional cash pay, minus unreimbursed work costs. If call or administrative work isn’t payable, account for it separately when comparing your workload. Include incentives only to the extent you reasonably expect to earn them.
Don’t count the same item twice. Paid time off is already reflected in your W-2 paid weeks. If you add the employer benefit value on one side, do not also subtract the equivalent replacement cost on the other. The comparison excludes income taxes, payroll taxes, self-employment taxes, deductions, and personal expenses.
The contract label doesn’t settle worker classification. For federal employment tax purposes, the IRS looks at the actual working relationship. A calculator comparing two offers cannot tell you whether a role should be classified as employment or independent contracting. Read the IRS guidance on worker classification.
Three things to get in writing before you accept
- Which hours are actually paid? Ask about guaranteed shifts, cancellation pay, call, charting time, and administrative work.
- Which expenses are reimbursed? Get the terms for travel, lodging, credentialing, and other costs. A verbal promise is not a useful number for your comparison.
- What does “malpractice included” mean for your assignment? Verify who is insured, which duties and sites are covered, and whether the policy is claims-made or occurrence. If claims-made coverage is involved, ask how claims can be reported after you leave and who is responsible for any needed tail. Read the AMA’s physician contracting guide.
If you expect to pay for tail yourself, you can spread the estimated cost over the years you expect to work in the role for comparison purposes. A hypothetical $24,000 expense over three years is an $8,000 annual reserve. That does not make it an $8,000 annual bill. Confirm how much would be due and when.
The hourly rate is clear. Is the malpractice coverage?
Bring the insurance clause or policy details to Samuel Bennett, licensed insurance agent at Island Insurance Group. We can help identify what to confirm with the staffing agency, employer, or carrier before you accept.
Schedule a malpractice coverage conversation