Changing Medical Malpractice Insurance in Florida: Before You Switch
Changing medical malpractice insurance in Florida requires more than choosing a new premium. Before ending your current policy, confirm how earlier patient care will be covered, what you must report to the current insurer, and when replacement coverage takes effect.
The most useful question is simple: If a patient makes a claim after I switch, which policy could respond to the care I provided before the change? Ask your agent to explain the answer using the actual policy terms.
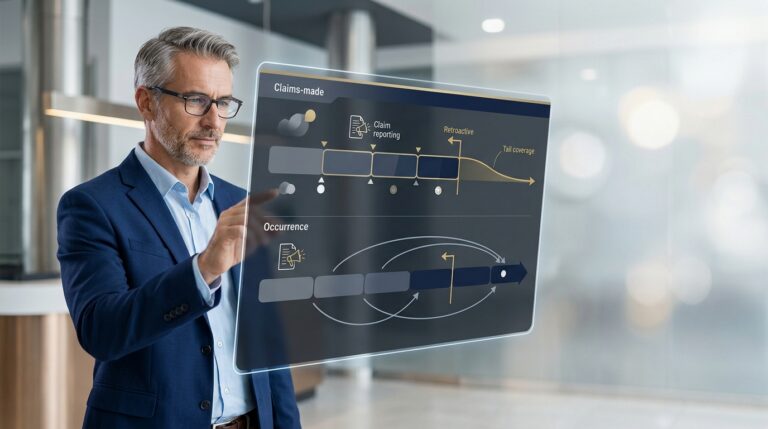
Does switching insurers mean you need tail coverage?
Not always. When a claims-made policy ends, tail coverage can extend the time to report eligible claims involving earlier care. Alternatively, the replacement insurer may offer prior acts coverage, sometimes called nose coverage. Tail does not insure new treatment after the old policy ends.
The Doctors Company explains these alternatives in its guide to extended reporting period coverage. Neither option should be assumed from a premium proposal alone.
Start your review by asking:
- Is my current policy claims-made or occurrence?
- Will the replacement policy address my earlier professional services?
- If tail is needed, what are its price, purchase deadline, duration, and conditions?
- If I am leaving an employer, what does my contract say about who pays?
Why is the retroactive date so important?
The retroactive date establishes a time boundary for eligible earlier professional services under a claims-made policy. Moving it forward can leave earlier work outside that policy.
But preserving the date is only one check. Confirm that the replacement terms also address the relevant physician, practice entity, services, locations, and exclusions. TDIA’s explanation of retroactive dates and prior acts emphasizes that an earlier date alone does not establish coverage for a particular claim.
Ask for a written explanation of any difference between the proposed coverage and the policy being replaced. Resolve discrepancies before relying on the transition.
What should you do about an existing claim or patient complaint?
Review the current policy’s claim and incident reporting requirements immediately. Do not wait for renewal shopping to finish if something may require notice. For example, The Doctors Company’s reporting guidance directs its insureds to notify the company promptly about claims or incidents that may lead to claims.
Follow your own insurer’s instructions, including the designated reporting channel. Ask whether a particular complaint, demand, or incident requires notice under your policy. Keep the submission and acknowledgment. Disclose underwriting information accurately; do not assume a new insurer will take responsibility for an already known matter.
What should Florida physicians check beyond the premium?
Review the applicable financial-responsibility rules separately from your insurance comparison. Florida Statutes section 458.320 addresses financial responsibility for physicians licensed under Chapter 458, with alternative methods and exemptions. It should not be reduced to a blanket statement that every Florida physician must buy the same policy.
Have the appropriate adviser confirm your requirements, including any hospital, employer, or other contractual obligations. This article does not determine an individual physician’s legal compliance.
For the insurance comparison itself, request written answers to these questions:
- Limits: What are the per-claim and aggregate limits? Are limits shared with anyone else?
- Defense: Do defense expenses reduce the available liability limit?
- Out-of-pocket costs: What deductible or retention applies, and to which expenses?
- Practice changes: Does the proposed coverage address your current procedures, locations, and professional roles?
- Transition costs: Are there tail costs, cancellation charges, or other fees to include in the comparison?
These are review questions, not statements that every policy has the same provisions. Island Insurance Group’s medical malpractice insurance services include reviewing policy structure, prior acts, and carrier transitions.
What documents should you gather before requesting alternatives?
Build a review packet so your agent can compare the current coverage with proposed terms:
- Current declarations page, full policy, and endorsements.
- Renewal offer or non-renewal notice, if applicable.
- Available carrier loss runs and a factual explanation of relevant claims.
- Current specialty, procedures, practice locations, and entities needing coverage.
- Relevant employment-contract provisions and written coverage requirements.
Ask what additional documents the prospective insurer needs. To organize physician underwriting questions, use the free medical malpractice assessment tool. Practice owners reviewing broader operational exposures can also use our separate free business assessment tool. Neither assessment establishes coverage.
What should be confirmed before canceling the current policy?
Use a final transition checklist with your agent:
- Obtain written confirmation that replacement coverage has been bound, with its effective date and conditions.
- Resolve how earlier care will be handled through the applicable prior-acts terms or tail arrangement.
- Complete required reporting to the current insurer and retain acknowledgments.
- Coordinate cancellation and replacement dates and retain the supporting documents.
- Review the issued policy and endorsements when received; promptly raise any discrepancy.
A quote is a proposal. Do not treat it as confirmation that coverage is in force.
Frequently asked questions
Do I always need tail coverage when changing malpractice insurers?
No. Suitable prior acts coverage from the replacement insurer may address earlier care instead. The actual terms determine whether tail is needed.
Is keeping my retroactive date enough?
No. Also review insured persons and entities, professional services, locations, exclusions, and reporting conditions.
Can changing carriers affect retirement tail benefits?
Yes. Eligibility may depend on continuous time with an insurer and other conditions. Check the current and proposed policies before switching.
For background on retirement eligibility conditions, see The Doctors Company’s tail coverage guidance.
Review the transition before you commit
Bring your current policy and proposed terms to Island Insurance Group for a review. If you are ready to explore alternatives, start with our supporting free medical malpractice insurance quote tool. Tool results are not binding coverage or guaranteed offers.
Samuel Bennett, Licensed Insurance Agent
sam@islandinsurancegroup.com
954-804-8144
Schedule an appointment
This article provides general insurance education, not legal advice. Coverage, eligibility, premiums, limits, exclusions, and availability depend on the applicant, policy, and insurer.