How to Reduce DSO Without Damaging Client Relationships
How to Reduce Days Sales Outstanding Without Damaging Client Relationships
Reducing Days Sales Outstanding does not require treating every customer like a collection problem.
In many businesses, slow payment is caused by preventable friction: invoices arrive late, billing contacts are incorrect, purchase-order information is missing or disputes remain unresolved.
The best DSO strategy removes those obstacles first and escalates deliberately when a customer still does not pay.
Calculate your starting DSO
Before changing the process, establish a baseline.
DSO = Accounts Receivable ÷ Credit Sales × Number of Days
Use figures from the same reporting period.
Calculate your current result with the free DSO Calculator. Record the method and use it consistently when measuring improvement.
1. Send invoices immediately
Every day an invoice waits internally adds a day to the collection cycle.
Create clear invoicing triggers:
- Project milestone completed
- Product delivered
- Service period ended
- Customer approval received
- Recurring billing date reached
Assign responsibility for generating and verifying the invoice.
2. Confirm the correct billing contact
The buyer may not be the person who processes payment.
Before issuing the invoice, confirm:
- Accounts-payable contact
- Billing email
- Required purchase-order number
- Vendor-portal requirements
- Supporting documentation
- Payment method
- Approval process
A reminder cannot solve an invoice that never reached the correct person.
3. Make invoices easy to understand
Invoices should clearly state:
- What was provided
- Amount due
- Invoice date
- Due date
- Payment terms
- Payment instructions
- Appropriate contact for questions
- Relevant project or purchase-order number
Ambiguous descriptions and unexplained charges create disputes and delays.
4. Confirm receipt of significant invoices
For high-value invoices, confirmation is worth the effort.
A short message can ask whether:
- The invoice was received
- Documentation is complete
- The correct person has it
- Any issue could delay approval
- Payment is scheduled
This is customer service and receivable management at the same time.
5. Use a pre-due-date reminder
A courteous reminder several days before the due date can prevent administrative delays.
The message should be helpful:
This is a quick reminder that invoice 1048 is due on September 15. Please let us know if you need another copy or supporting information.
Avoid language suggesting delinquency before the invoice is actually overdue.
6. Segment overdue accounts
Do not treat every overdue invoice equally.
Segment by:
- Days overdue
- Amount
- Customer history
- Recent communication
- Dispute status
- Broken promises
- Strategic importance
- Probability of recovery
Use the free Accounts Receivable Aging Calculator to identify where overdue balances are concentrated.
7. Establish a follow-up schedule
A practical schedule may include:
- Before due date: courtesy reminder
- Due date: payment-due notice
- 7 days overdue: friendly follow-up
- 15–30 days overdue: direct status request
- 31–60 days overdue: firmer follow-up
- 61–90 days overdue: management review
- More than 90 days overdue: escalation review
Adapt the schedule when an account is disputed or a payment arrangement exists.
8. Resolve disputes faster
Disputed invoices should be routed to a responsible person immediately.
Track:
- Amount disputed
- Reason
- Supporting documents
- Internal owner
- Expected resolution date
- Undisputed balance
- Next action
Sending repeated reminders without addressing the dispute can damage the relationship and prolong the delay.
9. Document promises to pay
Record the exact:
- Amount
- Payment date
- Payment method
- Person making the commitment
- Next action if payment is not received
A missed promise should trigger a defined follow-up.
10. Offer payment options carefully
When appropriate, approved payment arrangements may produce a better result than an all-or-nothing demand.
Document:
- Total amount
- Installment amounts
- Due dates
- Payment method
- Consequences of default
- Required internal approval
Review contractual, accounting and legal implications before changing payment obligations.
11. Reconsider payment terms
If DSO is consistently longer than the business can support, examine whether the original terms are appropriate.
Possible changes include:
- Deposits
- Progress billing
- Shorter terms
- Retainers
- Automatic recurring payments
- Credit limits
- Milestone payments
Do not change existing contractual terms unilaterally.
12. Use automation with human control
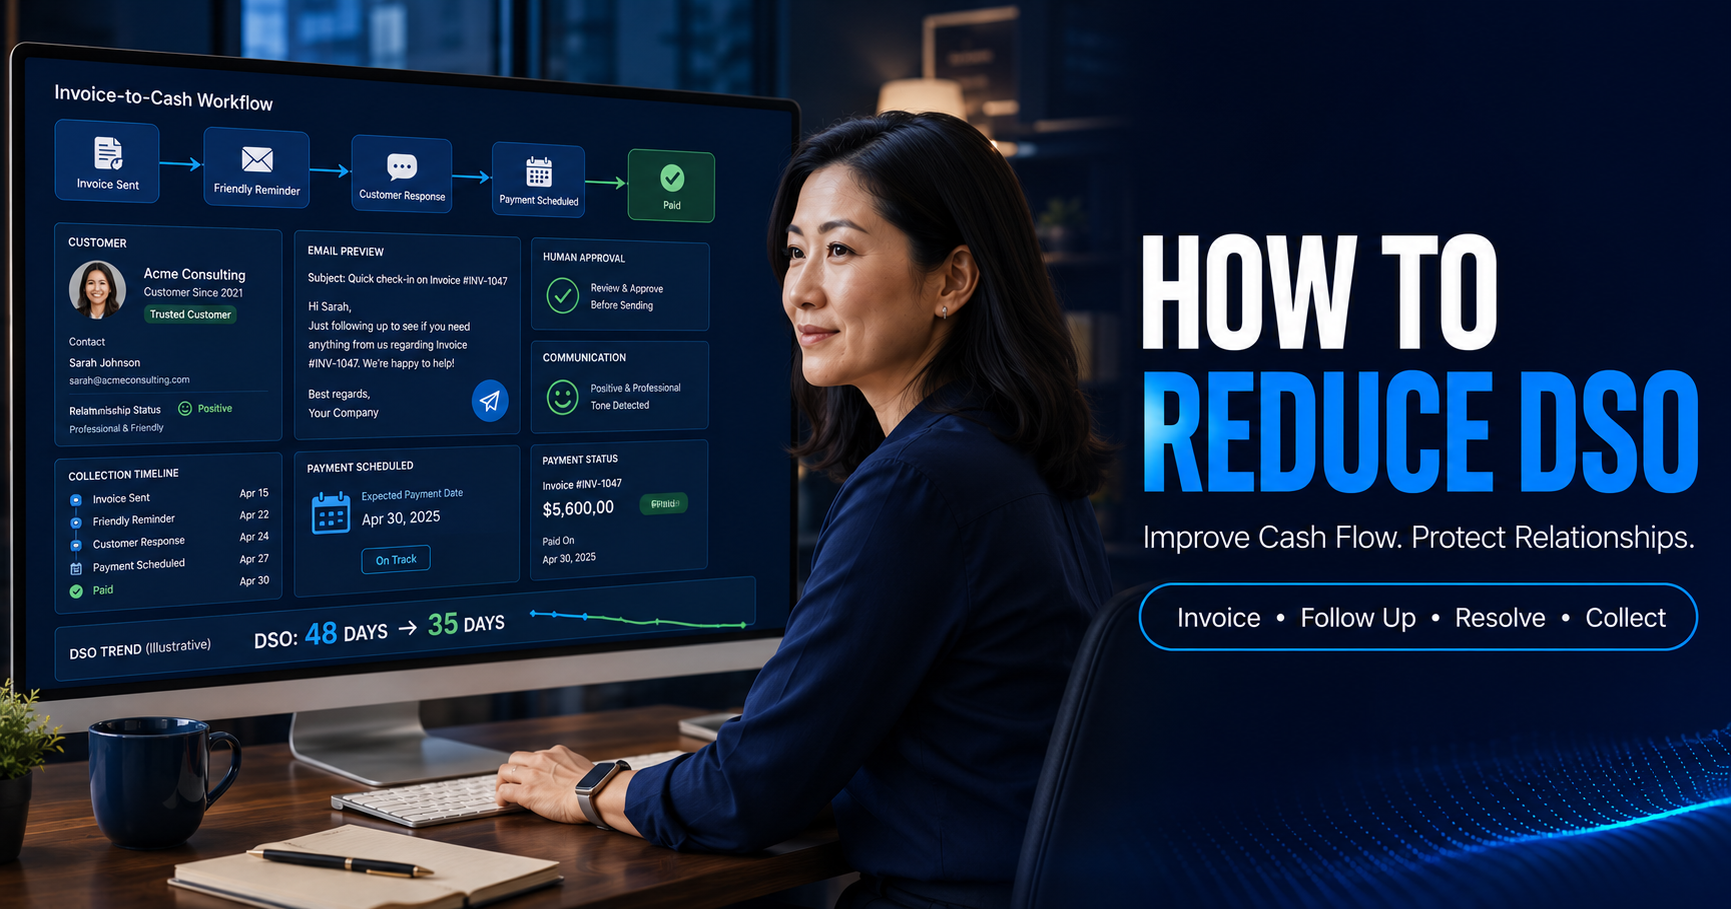
Automation can help:
- Identify accounts without recent contact
- Prepare reminder drafts
- Create follow-up tasks
- Surface high-priority balances
- Preserve collection history
- Monitor promises to pay
Customer-facing decisions still require context.
PaymentPilot’s AI accounts receivable software helps small businesses organize receivables and review recommended actions without surrendering human oversight.
13. Measure more than DSO
Monitor:
- Total overdue balance
- Percentage overdue
- Percentage more than 60 days overdue
- Dispute-resolution time
- Broken payment promises
- Follow-up completion
- Customer complaints
- Collection costs
Use the Late Payment Cost Calculator to estimate how delayed payments may affect financing costs, administrative effort and working capital.
Protect the relationship while improving cash flow
Professional collection communication should be:
- Accurate
- Timely
- Specific
- Respectful
- Consistent
- Appropriate to the aging stage
- Informed by the complete account history
Reducing DSO is not about sending more messages. It is about removing payment friction and ensuring every overdue invoice has a clear next action.
Explore PaymentPilot and start a 14-day free trial with no credit card required.
Review your broader business risks
Use the free Small Business Assessment Tool to identify other operational and insurance considerations.
You can also schedule a conversation with Samuel Bennett.
Samuel Bennett, Licensed Insurance Agent
sam@islandinsurancegroup.com
954-804-8144
This article provides general information. Payment terms, collection communications and escalation practices should be reviewed for contractual and legal appropriateness.