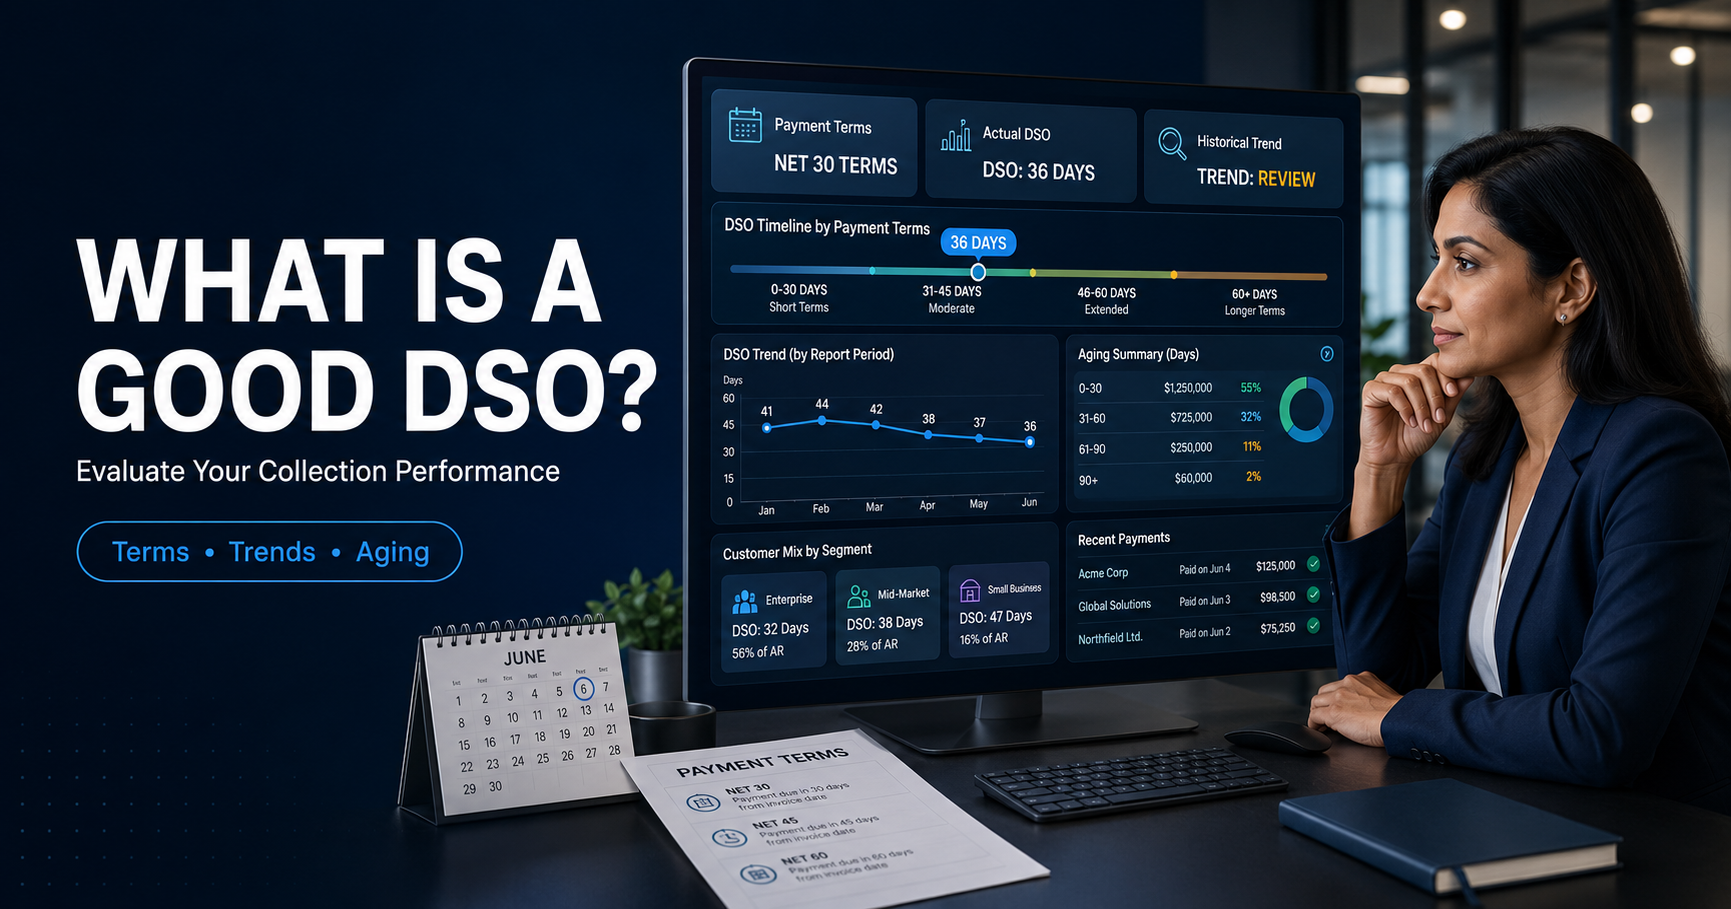
What Is a Good DSO? Evaluate Collection Performance
What Is a Good DSO? How to Evaluate Collection Performance
Business owners often want one universal Days Sales Outstanding benchmark.
They ask whether 30, 45 or 60 days is “good.”
That question sounds simple, but a benchmark without context can be misleading. A 45-day DSO may be concerning for a business with Net 15 terms and entirely understandable for one offering Net 60 terms.
A useful DSO evaluation begins with your own payment terms, historical performance and receivable composition.
What does DSO measure?
Days Sales Outstanding estimates the average number of days a business takes to collect its credit sales.
The basic formula is:
DSO = Accounts Receivable ÷ Credit Sales × Number of Days
Use the free PaymentPilot DSO Calculator to calculate your current result.
There is no universal good DSO
A good DSO is generally one that:
- Is reasonably aligned with payment terms
- Remains stable or improves over time
- Does not conceal severely aged balances
- Supports the business’s working-capital needs
- Reflects an effective invoicing and follow-up process
The goal is not always to force DSO as low as possible. Some businesses intentionally extend credit to win or retain valuable customers.
The real question is whether the additional collection time is deliberate, sustainable and adequately managed.
Compare DSO with payment terms
Payment terms provide the first reference point.
Suppose a business primarily offers Net 30 terms:
- A DSO near 30 days may indicate payments generally align with terms.
- A DSO of 40 days means collection extends roughly beyond the stated period.
- A DSO of 60 days suggests a more significant delay requiring investigation.
This is a simplified interpretation. Customer mix and invoice timing can affect the result.
Create a weighted view if customers operate under substantially different terms.
Compare DSO over time
The direction of the metric may be more valuable than the absolute number.
Track DSO:
- Month over month
- Quarter over quarter
- Year over year
- Before and after process changes
- By major customer segment, when possible
For example:
| Quarter | DSO |
|---|---|
| Q1 | 31 days |
| Q2 | 34 days |
| Q3 | 39 days |
| Q4 | 46 days |
No single quarter appears catastrophic, but the trend indicates progressive deterioration.
Compare DSO with aging
An average can hide serious collection risk.
Suppose most customers pay in 20 days while one large customer has an invoice more than 120 days overdue. The overall DSO may still look acceptable even though the aged balance deserves immediate attention.
Use the Accounts Receivable Aging Calculator to examine:
- Total receivables
- Total overdue
- Percentage overdue
- Percentage aged more than 60 days
- Balances more than 90 days overdue
DSO and aging answer different questions. Use them together.
Factors that influence an acceptable DSO
Payment terms
Longer contractual terms naturally produce a higher DSO.
Customer mix
Large organizations may have longer approval and payment processes than consumers or small businesses.
Billing frequency
Milestone billing, recurring billing and project completion invoicing produce different collection patterns.
Seasonality
A seasonal increase in invoicing near period-end may temporarily raise receivables.
Customer concentration
One large account can move the metric significantly.
Disputes
Unresolved billing or service disputes can extend collection time.
Industry practices
Customary payment cycles vary, but industry comparisons should use credible, comparable data.
When should a business be concerned?
Investigate when:
- DSO consistently exceeds normal payment terms
- DSO rises for several consecutive periods
- 60- and 90-plus-day balances are growing
- Customer disputes remain unresolved
- Broken payment promises are increasing
- Staff cannot explain the change
- Cash shortages develop despite strong sales
- Collection effort is consuming more employee time
A rising DSO is a signal—not a diagnosis.
Use 10 Reasons Your DSO Is Increasing to investigate the likely causes.
Avoid chasing a benchmark blindly
Reducing DSO at any cost can damage customer relationships.
Potential mistakes include:
- Sending aggressive reminders too early
- Shortening terms without customer communication
- Escalating disputed invoices automatically
- Applying one workflow to every customer
- Refusing reasonable payment arrangements
- Measuring employees only on collection speed
The objective is disciplined credit and collection management, not indiscriminate pressure.
Establish an internal DSO target
A useful internal target can consider:
- Standard payment terms
- Historical DSO
- Current cash-flow requirements
- Customer concentration
- Typical billing cycles
- Delinquency and dispute patterns
- Operational capacity for follow-up
Document how the target was chosen and review it when customer or business conditions change.
Improve the process behind the number
If DSO is higher than your business can support, focus on operational causes:
- Send invoices sooner
- Confirm billing contacts
- Reduce invoice errors
- Make payment instructions clearer
- Follow up consistently
- Resolve disputes faster
- Track promises to pay
- Prioritize aged and high-value balances
- Assign responsibility for each next action
Read How to Reduce DSO for a structured improvement plan.
From DSO measurement to receivable action
PaymentPilot’s accounts receivable software helps small businesses organize invoices, identify accounts requiring attention and manage follow-up with human oversight.
Calculate your DSO, compare it with payment terms and aging, and then investigate the invoices driving the result.
Additional small-business resources
Use the free Small Business Assessment Tool to examine additional operational and insurance concerns.
To discuss your business, schedule a 30-minute conversation.
Samuel Bennett, Licensed Insurance Agent
Island Insurance Group
sam@islandinsurancegroup.com
954-804-8144
No DSO number is universally appropriate. Results should be interpreted using consistent accounting methods and business-specific circumstances. This article is not accounting, financial or legal advice.