Why Is My Medical Malpractice Insurance Quote Taking So Long? 8 Common Reasons in Florida
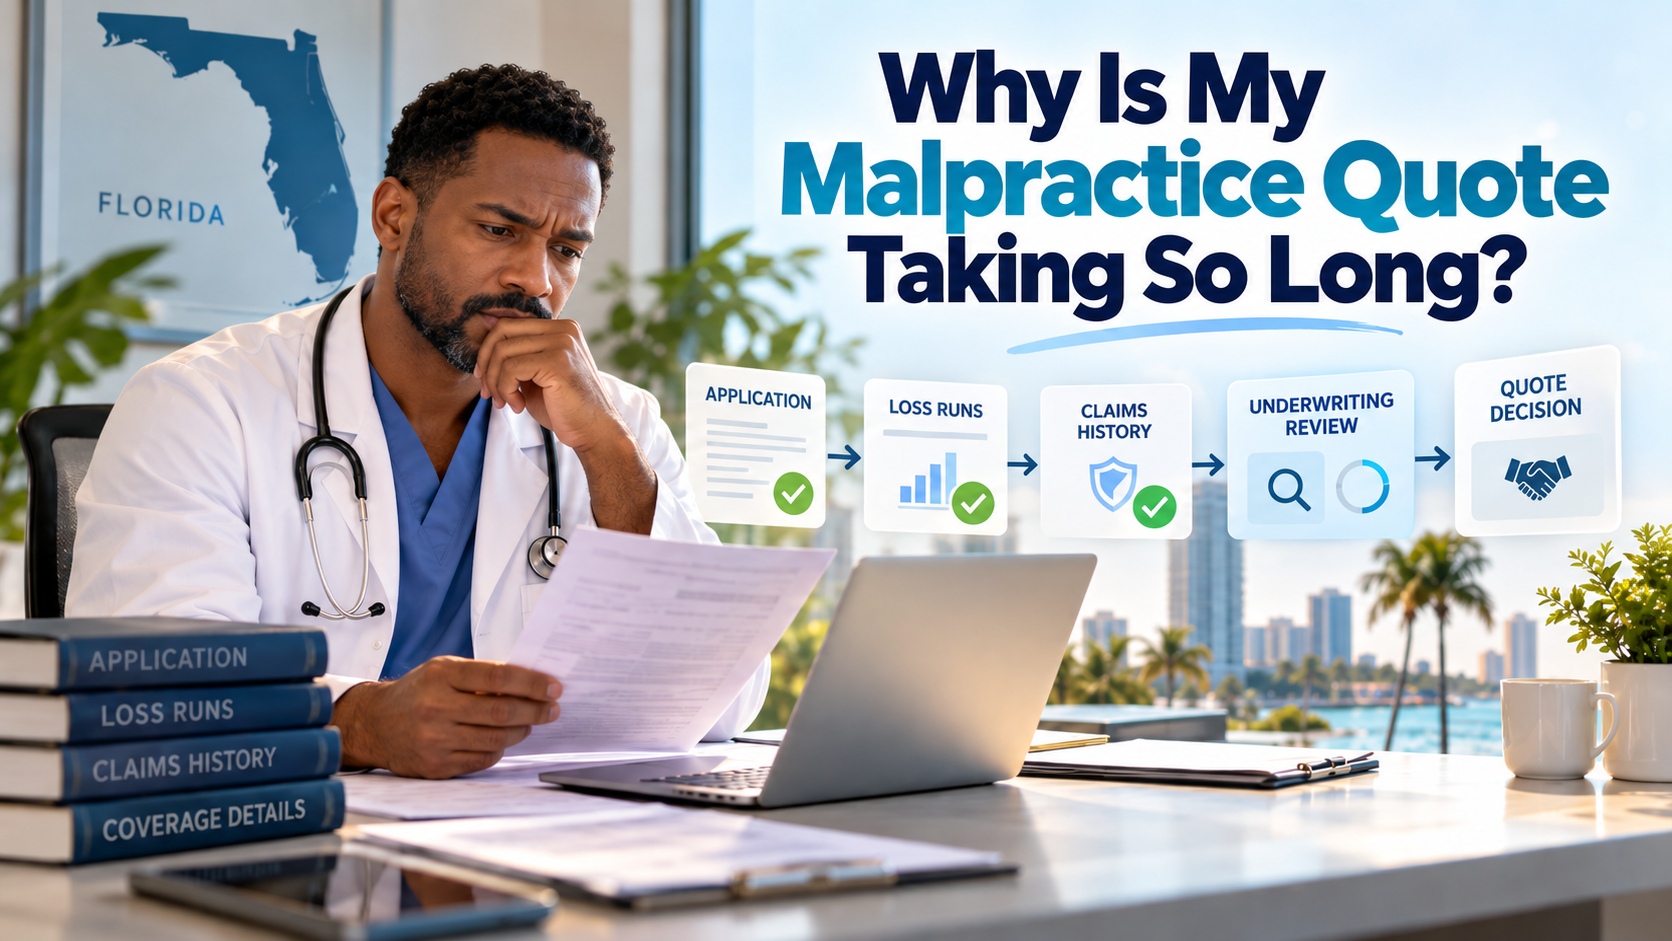
If your Florida medical malpractice insurance quote seems to be taking longer than expected, the delay does not necessarily mean the carrier is going to decline you.
Medical malpractice underwriting is rarely as simple as entering a few details and receiving a price. Before offering terms, an underwriter may need to understand your specialty, procedures, claims history, current coverage, retroactive date, practice locations, hospital affiliations, and other details that can materially change the risk.
The more complicated the physician’s profile, the more information the underwriter may need before making a decision.
If your quote appears stuck, here are eight areas worth checking.
1. The Underwriter Is Still Waiting for Your Loss Runs
Loss runs are among the most important documents in a medical malpractice submission. They provide the carrier’s record of claims, incidents, payments, reserves, and policy history.
A physician may tell an agent, “I only had one claim ten years ago,” but an underwriter will generally want documentation supporting the claims history rather than relying solely on the application.
A submission can slow down when:
- loss runs have not been received from a previous carrier;
- only some years of the requested history are available;
- a report is outdated;
- an open claim is missing current reserve information;
- the physician has been insured by several carriers; or
- the loss runs do not match answers provided on the application.
If this is the issue, requesting complete, currently valued records can help move the submission forward. Our guide on how to obtain medical malpractice loss runs explains the process step by step.
2. A Prior Claim Needs More Explanation
A claim appearing on a loss run is often only the beginning of the underwriting review.
The underwriter may want to know:
- What happened?
- When did the incident occur?
- What was the allegation?
- What was the physician’s involvement?
- Was the claim dismissed, settled, tried, or still open?
- Was an indemnity payment made?
- Are reserves still outstanding?
- Were any practice changes made afterward?
- Has anything similar occurred again?
This is why two physicians who each have one malpractice claim can receive very different underwriting responses.
The carrier is evaluating the circumstances surrounding the loss, not simply counting claims.
If you have prior claims, review our guide to medical malpractice insurance after a claim in Florida.
3. Your Application and Supporting Documents Do Not Match
Consistency matters.
Suppose the application states that a physician has practiced at one location for five years, but the CV lists three employers during that period. Or the application identifies one procedure while the practice website describes several additional procedures.
That does not automatically mean something is wrong.
It does mean the underwriter may need clarification before proceeding.
Other inconsistencies can involve:
- employment dates;
- practice locations;
- claims history;
- hospital privileges;
- board certification;
- procedure volume;
- hours worked;
- telemedicine activity;
- moonlighting or locum work; and
- the legal name of the insured entity.
Trying to move a submission faster by guessing at an application answer can create the opposite result. When information is uncertain, it is generally better to verify it before the application is submitted.
4. The Underwriter Needs More Detail About What You Actually Do
A specialty title does not always describe the actual exposure.
Two physicians may both identify themselves as internal medicine doctors while having dramatically different practices.
One may provide routine outpatient primary care.
Another may perform procedures, supervise advanced-practice clinicians, provide hospital care, work nursing-home rounds, practice telemedicine, or serve as a medical director.
Similarly, simply writing “surgeon,” “pain management,” “OB/GYN,” or “anesthesiology” may not provide enough information for underwriting.
Depending on the specialty, a carrier may request:
- a procedure list;
- estimated annual procedure volume;
- percentage of surgical versus nonsurgical work;
- hospital and ambulatory surgery center affiliations;
- patient volume;
- prescribing practices;
- supervisory responsibilities;
- telehealth activity;
- medical-director duties; or
- outside employment.
The goal is not to make the application difficult. The carrier needs to understand what it is actually being asked to insure.
5. Your Retroactive Date Has Not Been Confirmed
This can be especially important with claims-made medical malpractice insurance.
The retroactive date helps determine how far back potentially covered professional services can extend, subject to the terms and conditions of the policy.
If you are changing carriers, the new carrier may need to determine whether it can provide prior-acts coverage back to your existing retroactive date.
That can require reviewing:
- your current declarations page;
- previous policy information;
- coverage dates;
- employment history; and
- any potential gaps in insurance.
Do not cancel an existing claims-made policy merely because another carrier has provided an attractive preliminary price. Confirm the replacement effective date, retroactive date, prior-acts treatment, and any tail requirement before terminating existing coverage.
6. You Have an Open Claim
Open claims can create additional underwriting questions because the carrier does not yet know the final outcome or severity of the matter.
An underwriter may request:
- the allegations;
- current claim status;
- indemnity reserve;
- defense reserve;
- amounts already paid;
- your involvement in the matter;
- available claim documentation; and
- your attorney’s or carrier’s current assessment, when available and appropriate.
An open claim does not automatically mean that replacement coverage is unavailable. It does, however, usually require more information than a completely clean claims history.
7. There Is a Licensing, Board, Credentialing, or Disciplinary Issue
A “yes” answer to a professional-history question can trigger additional underwriting review.
The carrier may request documents concerning:
- a medical-board complaint;
- disciplinary action;
- license restrictions;
- hospital privilege issues;
- DEA matters;
- credentialing problems; or
- other disclosed regulatory matters.
This is one area where minimizing the issue can make underwriting harder rather than easier.
A complete submission should explain the facts accurately and include requested supporting documentation. Never omit a known claim, board matter, procedure, or other material fact simply because you are concerned that disclosure could affect the quote.
8. Your Risk Does Not Fit the First Carrier’s Underwriting Appetite
Sometimes the problem is not missing paperwork.
The risk simply does not fit a particular carrier.
Medical malpractice insurers have different underwriting appetites. A company may be comfortable with one specialty but restrict another. Some carriers may decline particular procedures, claims patterns, practice structures, or regulatory histories.
A physician who does not fit a standard carrier’s underwriting guidelines may still have other potential market options, including specialized or surplus-lines insurers, depending on the individual risk.
That does not mean coverage is guaranteed, and a non-admitted or surplus-lines policy should not be treated as interchangeable with an admitted policy. Policy terms, regulatory protections, exclusions, deductibles, defense provisions, consent-to-settle language, and other provisions need to be compared carefully.
What Should a Complete Medical Malpractice Submission Include?
Requirements vary by carrier, but a well-organized submission may include:
- a completed medical malpractice application;
- a current CV with an understandable work-history timeline;
- the current policy declarations page;
- currently valued loss runs;
- claim narratives when applicable;
- requested coverage limits;
- the existing retroactive date;
- practice locations;
- hospital and facility affiliations;
- procedure and patient-volume information;
- information about employed or supervised clinicians;
- medical-license and board-certification information;
- relevant disciplinary documentation;
- nonrenewal or cancellation notices when applicable; and
- the requested effective date.
Not every carrier will request every document. Complex risks can require additional information.
How Long Should You Wait Before Following Up on a Malpractice Quote?
There is no universal turnaround time.
A straightforward physician with a clean history and complete documentation may require much less underwriting than a surgeon with several claims, multiple facilities, an open matter, and years of prior-acts exposure.
Instead of repeatedly asking only, “Is the quote ready?” ask a more useful question:
Does the underwriter have everything necessary to make a decision?
If the answer is no, identify exactly what is outstanding.
If the answer is yes, your agent or broker can follow up with the underwriter regarding status.
Do Florida Physicians Have to Carry Medical Malpractice Insurance?
Florida’s rules are more nuanced than a simple yes-or-no insurance mandate.
Florida physicians are generally subject to financial-responsibility requirements, and professional liability insurance is one method of satisfying those requirements. Florida law also recognizes other methods and certain exemptions. Requirements can differ depending on circumstances such as hospital staff privileges.
For physicians licensed under Chapter 458, Florida Statute §458.320 addresses medical financial responsibility. Osteopathic physicians are addressed separately under §459.0085.
Insurance requirements imposed by a hospital, surgery center, employer, payer, staffing company, or other contract may also exceed statutory requirements.
This is one reason a physician should not select liability limits based only on a statutory minimum.
The Fastest Quote Is Not Necessarily the Best Quote
A physician facing a renewal deadline can understandably become focused on obtaining a price as quickly as possible.
But speed should not replace coverage review.
When proposals arrive, compare more than premium:
- claims-made versus occurrence coverage;
- retroactive date;
- prior-acts protection;
- tail provisions;
- per-claim and aggregate limits;
- deductibles;
- whether defense expenses reduce the liability limit;
- consent-to-settle provisions;
- covered professional services;
- covered entities and clinicians;
- locations;
- important exclusions; and
- carrier and policy structure.
A lower premium can become expensive if the proposal fails to protect exposure you intended to insure.
Find Out What an Underwriter May See Before You Request Quotes
If you are preparing for a malpractice renewal, have previous claims, received a nonrenewal, changed procedures, or simply want to understand your risk profile better, start with the free medical malpractice assessment tool.
The assessment is educational and is designed to help identify underwriting factors that may deserve attention before or during the quotation process. It is not an insurance quote, binder, offer of coverage, or guarantee that a carrier will provide terms.
You can also review Florida medical malpractice insurance options through Island Insurance Group.
Ready to Request a Medical Malpractice Quote?
Once your underwriting information is organized, you can use the free medical malpractice quote tool to begin the quotation process.
Coverage availability, premiums, limits, exclusions, and policy terms remain subject to carrier underwriting and the information provided with the application.
Samuel Bennett, Licensed Insurance Agent
Island Insurance Group
Email: sam@islandinsurancegroup.com
Phone: 954-804-8144
Schedule a 30-minute appointment
Frequently Asked Questions
Why is my medical malpractice insurance quote taking so long?
A quote may be delayed because an underwriter needs additional loss runs, claim information, procedure details, a current declarations page, clarification of employment history, regulatory documents, or confirmation of a retroactive date. More complicated risks generally require more underwriting.
Do prior malpractice claims automatically cause a decline?
No. A previous claim does not automatically determine the outcome. Carriers can consider factors such as claim frequency, severity, status, payments, specialty, procedures, overall history, and whether similar events have occurred repeatedly. Eligibility depends on the individual carrier and risk.
What documents should I have ready for a malpractice quote?
Common requests include a completed application, CV, current declarations page, valued loss runs, requested limits, retroactive date, practice locations, procedure information, and explanations of prior claims or regulatory matters. Additional documentation may be required depending on the physician and carrier.
Can I get malpractice insurance if I have an open claim?
Potentially. An open claim can require additional underwriting because its eventual severity may still be uncertain. Availability and terms depend on the physician’s complete history, claim details, specialty, carrier guidelines, and other underwriting factors.
Should I cancel my current malpractice policy after receiving a new quote?
Not simply because you have received a quote. Before terminating existing claims-made coverage, confirm that replacement coverage is actually approved and coordinate the effective date, retroactive date, prior-acts protection, tail requirements, and other conditions.
Can Island Insurance Group help with difficult-to-place physicians?
Island Insurance Group works with Florida physicians and medical practices, including accounts involving prior claims, nonrenewals, difficult specialties, regulatory history, and other circumstances that may require specialized underwriting. Market access and coverage remain subject to individual carrier eligibility and underwriting.
This article provides general insurance information and is not legal advice. Insurance eligibility, availability, premiums, limits, exclusions, terms, and conditions vary by carrier and individual risk. Coverage is determined by the issued policy and applicable endorsements.