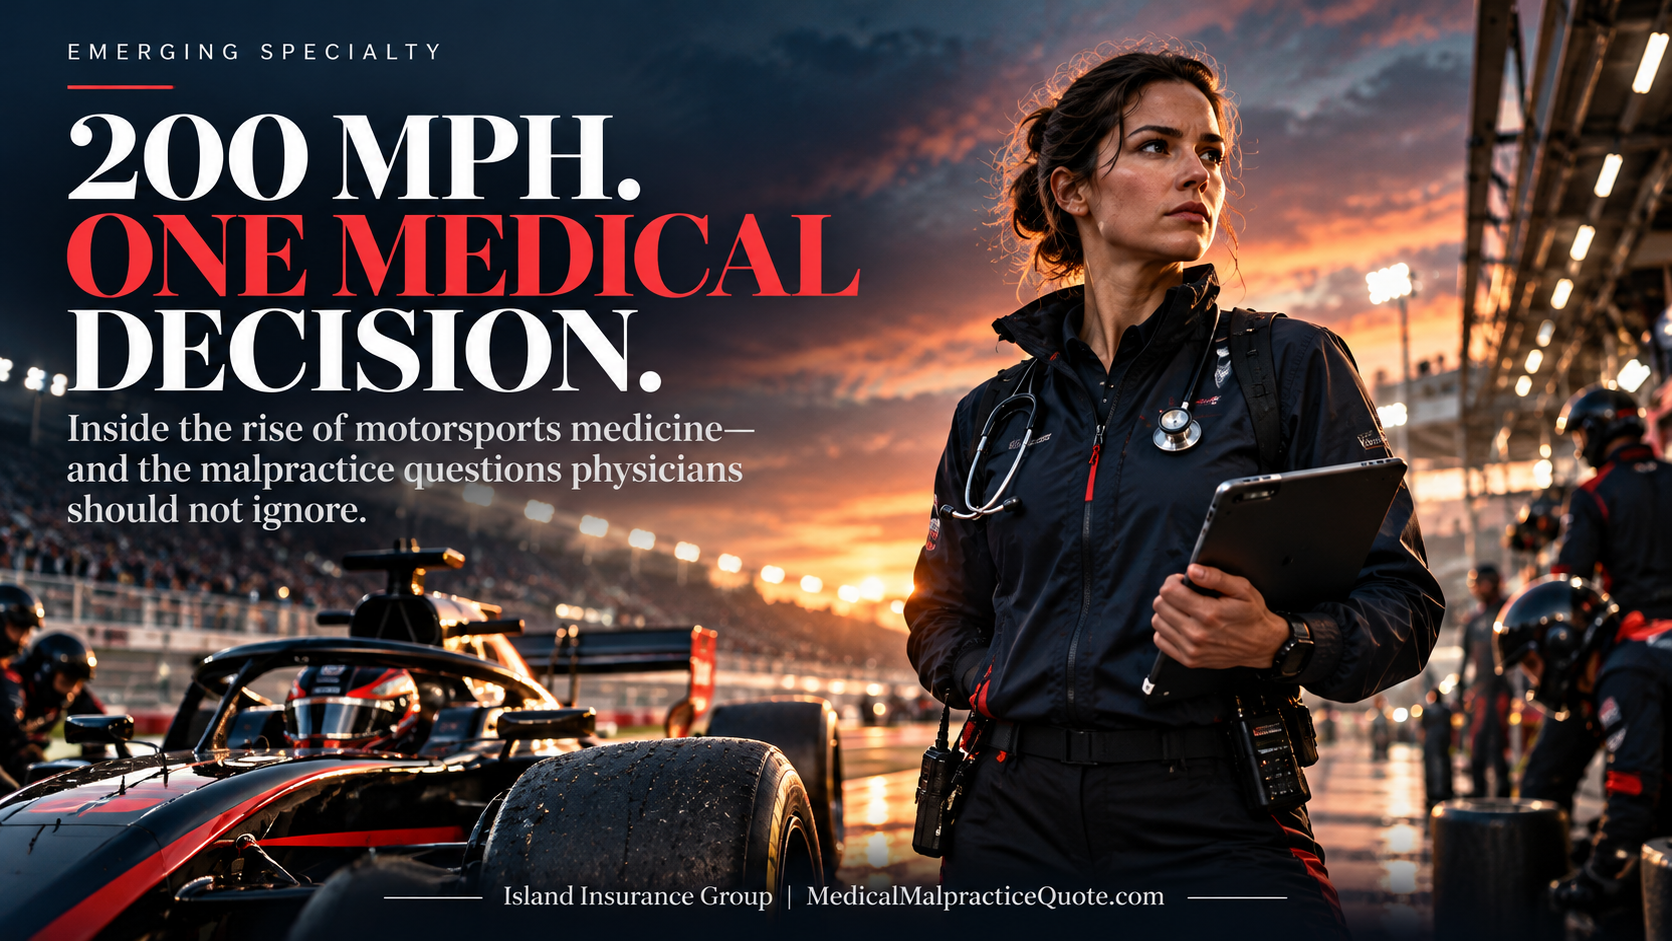
Motorsports Medicine Is Growing. But Are the Doctors Behind the Wheel Protected?
Motorsports medicine is moving into the spotlight, but a critical insurance question deserves attention: Does a physician’s existing medical malpractice policy cover professional services provided at a racetrack?
For doctors working in emergency medicine, sports medicine, trauma care, rehabilitation, and event medicine, the answer may depend on the specific duties performed, the location of treatment, the physician’s contractual relationship, and the actual policy language.
As motorsports medicine develops into a more specialized field, physicians need to understand not only the clinical demands of the racetrack but also the professional liability exposure associated with providing care in an unconventional environment.
A New Frontier in Medicine Is Emerging at High Speed
On February 16, 2026, The DO, a publication serving the osteopathic medical profession, published an article titled “Motorsports medicine: An emerging subspecialty ripe for growth.”
The article examined a field that brings together emergency medicine, sports medicine, injury prevention, recovery, and human performance.
Racecar drivers experience unusual physical demands, including acceleration forces, extreme temperatures, vibration, and sustained cognitive pressure.
When crashes occur, medical personnel may have to assess and treat injured drivers under circumstances that differ substantially from those of a conventional clinical setting.
These realities create opportunities for physicians with specialized skills. They also raise important questions about how professional liability insurance responds to trackside medical activities.
What Exactly Does a Motorsports Physician Do?
Motorsports medicine can involve more than treating injuries after an accident.
Depending on the organization and assignment, physicians may participate in:
- Trackside emergency medical response
- Trauma assessment and stabilization
- Concussion evaluation and return-to-competition decisions
- Heat-related illness assessment and treatment
- Pre-event medical screening
- Musculoskeletal injury evaluation
- Sports medicine and rehabilitation services
- Medical oversight of event response teams
- Planning medical protocols and emergency response procedures
Professional motorsports organizations already use specialized medical teams.
For example, INDYCAR and Indiana University Health have publicly described a medical program involving physicians and nurses with expertise in motorsports medicine. Indiana University School of Medicine also established a dedicated motorsports medicine fellowship in 2020.
These developments demonstrate that motorsports medicine is more than an occasional volunteer assignment. It is an area of increasingly organized clinical practice.
The Malpractice Insurance Question That Deserves More Attention
Imagine an emergency physician who maintains a professional liability policy for clinical work at a Florida hospital.
The physician is invited to provide medical coverage at a weekend motorsports event.
During the event, the physician may be expected to assess an injured driver, direct an emergency response, or participate in a decision about whether an athlete can safely return to competition.
Does the physician’s existing malpractice policy cover those services?
That should be verified before accepting the assignment.
Some professional liability policies may cover certain outside medical activities. Others may restrict coverage according to the insured’s declared specialty, employer, locations, contracted responsibilities, or specifically described professional services.
Coverage may also depend on whether the physician is employed by the event organizer, independently contracted, volunteering, or operating through a medical practice entity.
No physician should assume that coverage automatically follows their medical license to every clinical environment.
Five Professional Liability Questions Every Trackside Physician Should Ask
1. Does My Policy Cover Care Outside My Normal Practice?
A physician’s existing policy may have been underwritten around a particular role, location, or set of procedures.
Providing emergency services at a racetrack may involve responsibilities not specifically contemplated when that policy was issued.
The physician should confirm with the insurer or authorized representative whether the proposed activities fall within the scope of covered professional services.
2. Are Emergency Procedures and Trackside Interventions Covered?
Motorsports medical assignments may involve emergency stabilization, trauma care, airway management, or other procedures performed under difficult conditions.
Underwriters may need details about the physician’s actual activities, clinical training, available equipment, and responsibility within the medical team.
The fact that a physician is qualified to perform a procedure does not, by itself, establish that every activity is insured.
3. Who Is Providing the Insurance: The Physician or Event Organizer?
A racetrack, motorsports organization, medical staffing company, or event organizer might arrange insurance for some medical personnel.
However, a statement that an event has insurance does not establish that every participating physician is covered for professional negligence.
Physicians should request documentation identifying the insurer, named insureds, covered activities, policy limits, exclusions, and applicable conditions.
They should also determine whether the coverage is primary, excess, or subject to coordination with their individual policies.
4. Are Medical Director and Supervisory Responsibilities Included?
A physician providing direct patient care may have a different responsibility profile from one directing medical operations at an event.
Medical directors may help establish treatment protocols, oversee personnel, coordinate emergency response, or make decisions about medical readiness.
These responsibilities should be disclosed and evaluated when arranging professional liability coverage.
5. What Happens if the Event Takes Place in Another State?
Physicians who work at events in multiple states should examine both professional licensing requirements and insurance territorial provisions.
A policy issued for a Florida physician should not automatically be assumed to cover every out-of-state motorsports assignment.
Licensure, permitted activities, policy jurisdiction, and contractual obligations require separate review.
Two Physicians at the Same Race. Two Different Insurance Exposures.
Consider the following fictional example.
Physician A: A sports medicine physician provides scheduled evaluations and follow-up care for drivers through a medical practice.
Physician B: An emergency physician provides trackside trauma response and also serves as the event’s medical director.
Both physicians are working in motorsports medicine, but their professional activities differ considerably.
An insurance underwriter might need to evaluate different procedures, response responsibilities, medical protocols, contracts, locations, and limits for each physician.
The lesson is simple: The description “motorsports medicine” is not enough to determine the appropriate insurance coverage.
Underwriters need to understand what the physician actually does.
Florida Physicians Have Additional Considerations
Florida is home to prominent motorsports venues and events, including Daytona International Speedway and Homestead-Miami Speedway.
For physicians considering event medical work in Florida, professional liability insurance deserves attention alongside licensing, contracts, and clinical responsibilities.
Florida Statute 458.320 establishes financial responsibility requirements for physicians licensed under Chapter 458, including specified methods of compliance and certain exemptions.
However, satisfying applicable state financial responsibility requirements does not automatically mean that a particular racetrack assignment is covered under a physician’s existing malpractice policy.
Event contracts and medical staffing agreements may also impose separate insurance requirements.
Physicians should review these obligations before beginning services, particularly when work is outside their usual practice setting.
Could Motorsports Medicine Require Specialized Malpractice Underwriting?
Potentially, depending on the individual physician’s role and the insurer’s guidelines.
An underwriter evaluating a motorsports medical assignment may request information about:
- The physician’s primary medical specialty
- Training and experience relevant to the assignment
- Specific procedures and professional duties
- Whether emergency medical services are provided
- Frequency and duration of event participation
- Event locations and jurisdictions
- Employment, volunteer, or independent contractor status
- Medical director or supervisory responsibilities
- Existing malpractice insurance and loss history
- Available event-sponsored professional liability coverage
Some risks may fit an insurer’s existing underwriting guidelines. Others may require further review or consideration of different coverage arrangements.
Market eligibility and coverage availability cannot be determined from specialty alone.
Before Accepting a Racetrack Medical Assignment, Review This Checklist
- ☐ Obtain a written description of your clinical responsibilities.
- ☐ Review the event’s medical staffing contract.
- ☐ Confirm whether you are covered under an employer or event-sponsored policy.
- ☐ Request and review applicable professional liability insurance documentation.
- ☐ Verify that trackside procedures and emergency activities are within your policy’s covered services.
- ☐ Confirm applicable policy limits, exclusions, and territorial provisions.
- ☐ Determine whether medical director or supervisory responsibilities require additional coverage.
- ☐ Review any claims-made retroactive-date and extended-reporting requirements.
- ☐ Confirm applicable state licensing and credentialing obligations.
- ☐ Obtain written clarification from the appropriate insurer or authorized representative before beginning unfamiliar duties.
Taking these steps cannot eliminate every liability risk, but it can help identify important insurance questions before an incident occurs.
How Can Physicians Explore Their Medical Malpractice Insurance Profile?
Physicians interested in motorsports medicine should begin by understanding their existing professional liability coverage and identifying how any additional work changes their exposure.
Island Insurance Group provides a free medical malpractice quoting and underwriting analysis tool designed to help physicians explore estimated premium ranges and general risk characteristics.
The platform offers a starting point for discussions about specialty, professional activities, and potential underwriting considerations.
Important: The online tool is not a substitute for reviewing unusual motorsports medical assignments with a licensed insurance professional. Its estimates do not confirm that a racetrack activity is covered or that a carrier will offer a policy.
Explore the Free Medical Malpractice Quoting Tool →
Physicians who want to organize relevant underwriting information before seeking formal coverage can also use our free medical malpractice assessment tool.
Frequently Asked Questions About Motorsports Medicine Insurance
Does medical malpractice insurance cover physicians working at racetracks?
It may, but coverage depends on the policy, insured activities, locations, contractual arrangements, and other conditions. Physicians should obtain confirmation that their intended duties are covered.
Do motorsports organizations provide malpractice insurance for their doctors?
Some organizations may arrange insurance for participating medical personnel, but coverage varies. Physicians should review actual professional liability policy terms rather than assuming that general event insurance includes medical malpractice protection.
Do volunteer racetrack physicians need malpractice insurance?
Volunteer status alone does not establish insurance coverage or immunity from liability. The nature of the services, applicable laws, event arrangements, and any available policies should be reviewed before participation.
Does a sports medicine malpractice policy cover emergency trauma response?
Not necessarily. A policy covering routine sports medicine services should not be assumed to include all emergency trauma procedures or trackside response responsibilities. The insurer may need to evaluate the physician’s actual activities.
Can a Florida physician get a malpractice quote for motorsports medical work?
A physician can request an underwriting review describing the proposed assignment. Whether coverage is available depends on the insurer, professional duties, credentials, jurisdiction, and other risk characteristics.
The Future of Motorsports Medicine Requires More Than Clinical Expertise
As motorsports medicine continues to develop, physicians may find new opportunities to apply their expertise in emergency care, sports medicine, trauma management, and athlete performance.
But specialized clinical opportunities can bring unfamiliar insurance questions.
Before providing medical services at a racetrack, physicians should understand who is responsible for the coverage, which activities are insured, and whether their existing professional liability arrangements are sufficient for the assignment.
The right time to resolve those questions is before the race begins.
Explore your current malpractice insurance profile with MedicalMalpracticeQuote.com, or contact Island Insurance Group to discuss professional liability coverage for specialized physician responsibilities.
Samuel Bennett, Licensed Insurance Agent
Island Insurance Group
Email: sam@islandinsurancegroup.com
Phone: 954-804-8144
Schedule a 30-Minute Insurance Consultation
Disclaimer: This article is for general educational purposes and does not provide legal advice, confirm insurance eligibility, or establish coverage under any policy. Actual terms, exclusions, limits, eligibility, and availability depend on the insurer, applicant, and policy language.