Accounts Receivable Process for Small Businesses
Accounts Receivable Process for Small Businesses: A Step-by-Step Guide
Making a sale does not improve cash flow until the customer pays.
That distinction causes problems for many small businesses. Revenue may look healthy on paper while unpaid invoices consume working capital, administrative time and attention.
A consistent accounts receivable process helps prevent invoices from disappearing into spreadsheets and inboxes. It establishes what should happen from the moment an invoice is created until the balance is paid or escalated.
This guide explains how to create a practical accounts receivable process without making every customer interaction feel like a collection call.
What is the accounts receivable process?
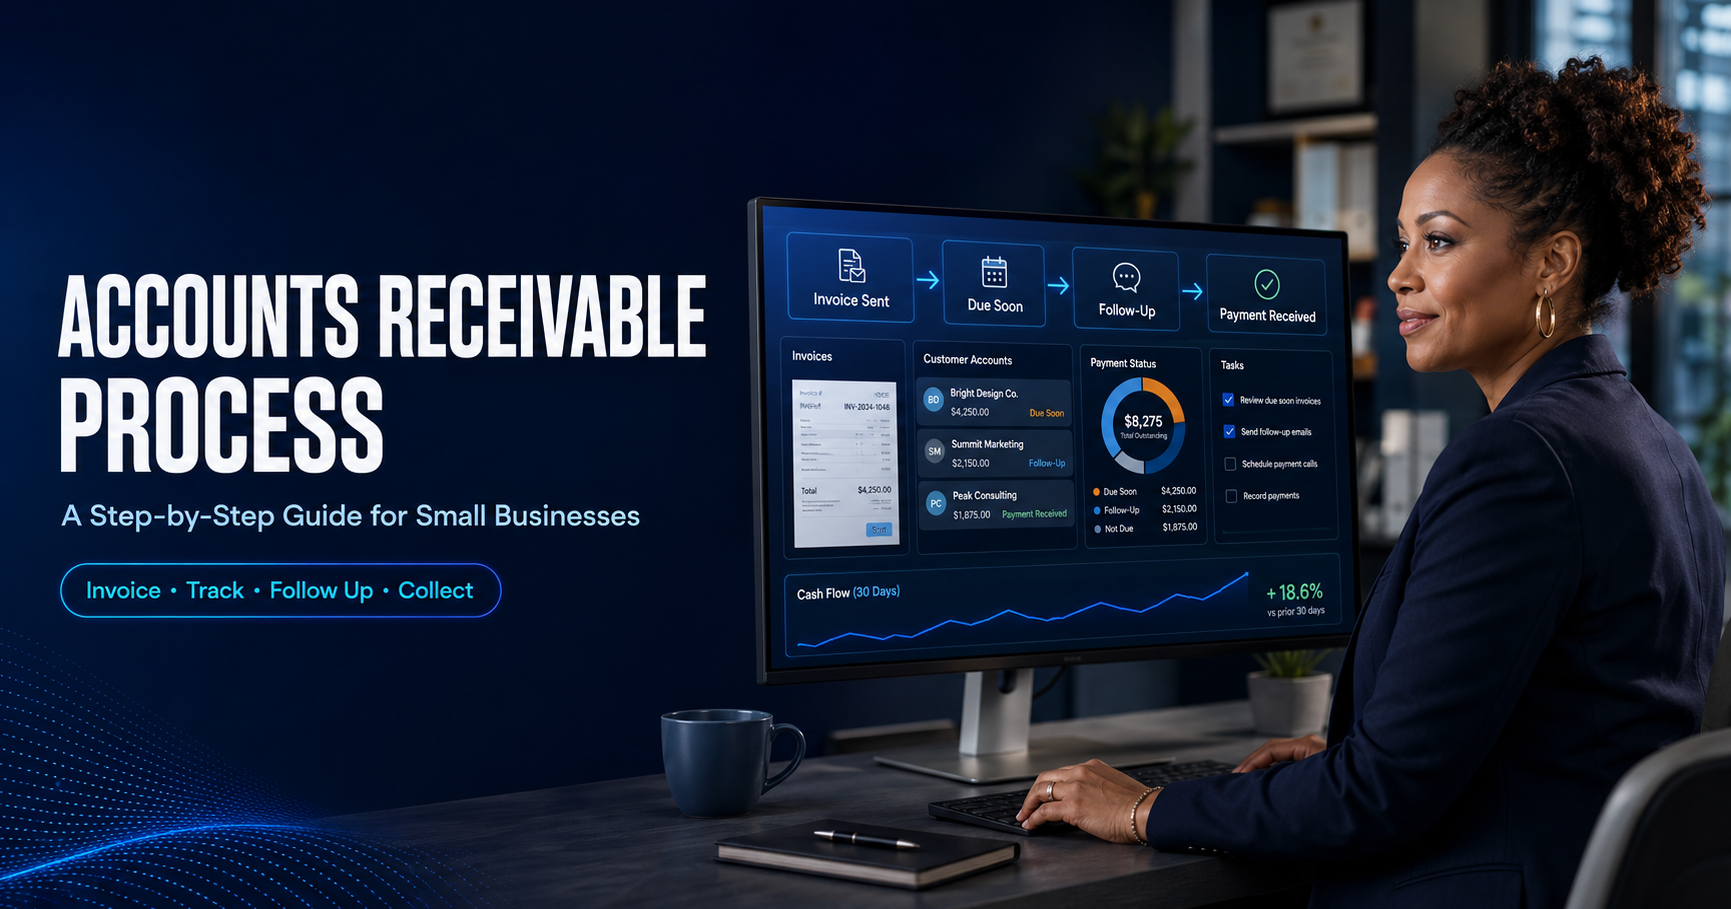
The accounts receivable process covers the steps a business uses to invoice customers, monitor outstanding balances, follow up on payments, document account activity and address overdue invoices.
A typical process includes:
- Establishing payment terms
- Creating and delivering an accurate invoice
- Confirming that the customer received it
- Monitoring the payment due date
- Sending reminders
- Recording promises, disputes and communications
- Escalating seriously overdue balances
- Applying the payment and closing the invoice
The weakness in many small businesses is not invoicing. It is what happens between sending the invoice and receiving payment.
Step 1: Establish clear payment terms
Payment expectations should be documented before work begins.
Your agreement should identify:
- The amount being charged
- The invoicing schedule
- The payment due date
- Accepted payment methods
- Any approved late-payment terms
- The person responsible for billing questions
- The process for disputing an invoice
Payment terms such as Net 15, Net 30 or due upon receipt should be selected intentionally. Offering every customer the same terms without evaluating the relationship or project may unnecessarily delay cash flow.
Any late fees, interest or collection charges should be reviewed for contractual and legal compliance before use.
Step 2: Send accurate invoices promptly
An invoice cannot be paid if it was never sent, went to the wrong person or contained incorrect information.
Each invoice should include:
- Your legal business name and contact information
- The customer’s correct billing information
- A unique invoice number
- A clear description of the product or service
- The invoice date and due date
- The total amount due
- Payment instructions
- The applicable purchase order or project number
Send invoices as soon as the applicable milestone is completed. Waiting until the end of the week or month creates avoidable delays.
Step 3: Centralize invoice information
Small businesses frequently track balances in one system, emails in another and promises to pay in someone’s personal notes.
That fragmentation makes it difficult to answer basic questions:
- Which invoices are overdue?
- Who received a reminder?
- Which customer promised to pay?
- Is an invoice disputed?
- What should happen next?
- Who is responsible for following up?
Centralizing this information creates accountability and reduces duplicated work.
PaymentPilot’s AI accounts receivable software is designed to organize invoices, customer activity, recommended next actions and collection follow-up in one workflow while keeping the user in control.
Step 4: Monitor accounts receivable aging
An accounts receivable aging report separates balances into time-based categories:
- Current
- 1–30 days overdue
- 31–60 days overdue
- 61–90 days overdue
- More than 90 days overdue
Aging reveals where unpaid money is accumulating. It also helps the business avoid treating a five-day delay like a 95-day delinquency.
Use the free Accounts Receivable Aging Calculator to organize balances by aging category and identify where collection risk may be increasing.
Step 5: Prioritize collection activity
Following up in alphabetical order is not a collection strategy.
Businesses should consider factors such as:
- Amount outstanding
- Number of days overdue
- Previous payment behavior
- Recent communication
- Broken payment promises
- Active invoice disputes
- Importance of the customer relationship
- Likelihood of recovery
A large invoice that is 60 days overdue may require more immediate attention than several small balances that became due yesterday.
Prioritization helps limited staff focus on the accounts most likely to affect cash flow.
Step 6: Use a consistent follow-up schedule
A basic schedule might include:
- Several days before the due date: courteous reminder
- Due date: payment-due notification
- 7 days overdue: friendly follow-up
- 15–30 days overdue: direct status request
- 31–60 days overdue: firmer follow-up and internal review
- 61–90 days overdue: escalation and payment-resolution discussion
- More than 90 days overdue: management review and possible external action
This schedule should be adapted to the customer, contract and circumstances. Automation can improve consistency, but messages should not ignore disputes, payment arrangements or sensitive relationships.
Step 7: Document every important interaction
Record:
- Date and method of contact
- Person contacted
- Response received
- Payment promise
- Expected payment date
- Dispute or concern
- Supporting documents requested
- Next follow-up date
- Person responsible for the next action
Documentation prevents confusion and creates continuity when multiple employees are involved.
Step 8: Track collection performance
Days Sales Outstanding, or DSO, estimates how long it takes a business to convert credit sales into cash.
The basic formula is:
DSO = Accounts Receivable ÷ Credit Sales × Number of Days
Use PaymentPilot’s free DSO Calculator to calculate your result using figures from the same reporting period.
DSO should be interpreted alongside payment terms, customer mix, seasonality and industry conditions. One number should not be treated as a universal performance grade.
Step 9: Define an escalation process
Your team should know when an overdue invoice requires management review.
Escalation may involve:
- Confirming there is no unresolved dispute
- Suspending additional credit
- Requesting a payment plan
- Sending a formal notice
- Reviewing contractual remedies
- Consulting legal counsel
- Referring the account to an appropriate collection provider
Escalation decisions should consider the balance, documentation, customer relationship, recovery prospects and applicable law.
Turn the process into a repeatable workflow
A strong accounts receivable process is not simply a series of reminder emails. It connects payment terms, invoicing, aging, prioritization, communication and escalation.
PaymentPilot helps small businesses see which accounts need attention, review suggested next actions and maintain a clearer collection history.
Explore PaymentPilot’s AI accounts receivable software and start a 14-day free trial with no credit card required.
Additional business resources
Late payments are only one risk facing a growing business. Use the free Small Business Assessment Tool to identify operational and insurance considerations that may deserve attention.
To discuss your business risks, schedule a 30-minute conversation.
Samuel Bennett, Licensed Insurance Agent
Island Insurance Group
sam@islandinsurancegroup.com
954-804-8144
PaymentPilot provides business software and AI-assisted recommendations. Users should review recommendations before acting. This article provides general information and is not legal, accounting or financial advice.