Florida Medical Malpractice Insurance Quotes: 7 Checks Before You Buy
To compare Florida medical malpractice insurance quotes, review the coverage terms alongside the premium: policy form, prior acts, limits, defense costs, settlement control, insured parties, and covered work. A lower price is useful only when you understand what protection comes with it.
For a physician renewing coverage, joining a group, or changing carriers, the practical question is simple: does the proposed policy fit the care you provide and the obligations you already have?
What documents should you request before comparing quotes?
Ask for the written quote, specimen policy, proposed endorsements, and a complete list of conditions that must be satisfied before coverage can begin. Compare them with your current declarations page and policy endorsements.
A certificate alone is not enough for this review. Build a comparison sheet with one column for your existing coverage and one for each proposed option. Mark unanswered questions as unresolved rather than assuming the terms match.
1. Are you comparing the same policy form?
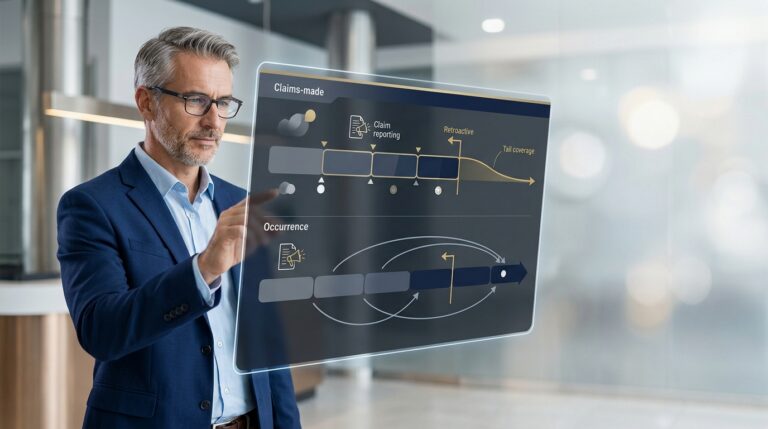
Identify whether each option is claims-made or occurrence coverage. The NAIC explains that claims-made coverage is tied to the claim-reporting period, while occurrence coverage is tied to when the covered event happened. Exact triggers and reporting requirements depend on the policy. Source: NAIC medical malpractice insurance overview.
Ask the agent to explain how each quote would respond to a claim reported after you leave the insurer. Do not assume a lower annual premium also means a lower total cost when you later change jobs or retire.
2. What happens to your prior acts?
For a claims-made comparison, ask the proposed insurer to confirm the retroactive date and explain any restrictions on prior-acts protection. If replacement coverage will not protect earlier work, ask what extended-reporting coverage, commonly called tail coverage, may be needed from the existing insurer.
Request a written explanation of how known claims, reported circumstances, and any gaps would be handled. Do not cancel the current policy based on an assumption that the replacement will cover everything.
For help organizing the review, explore Island Insurance Group’s Florida medical malpractice coverage services.
3. Do the limits and deductible match your obligations?
Compare the per-claim limit, aggregate limit, and deductible or retention. Ask whether limits are individual or shared, and whether the practice entity has separate protection.
For a Florida physician, put hospital credentialing requirements, employment agreements, and locum or staffing contracts beside the quotes. Have the relevant organization confirm its requirements. A quote should not be accepted solely because its limits resemble those on last year’s policy.
- What amount applies to a single covered claim?
- What total amount is available under the aggregate?
- Which insureds share that aggregate?
- Does the deductible or retention apply to defense expenses, indemnity payments, or both?
4. How are defense expenses treated?
Ask whether defense expenses reduce the liability limit, whether there is a separate defense limit, and how your deductible or retention applies. Request the provision supporting the answer.
Hypothetical example: If a policy has a $1 million liability limit and $200,000 of defense expenses reduce that same limit, $800,000 would remain before other applicable payments or terms. This is arithmetic illustrating one possible structure, not a prediction of claim costs or a description of a particular insurer.
Two quotes with the same headline limit may therefore need different explanations before you can compare them fairly.
5. Who controls settlement?
Ask for the consent-to-settle provision and any language addressing disagreement with a proposed settlement. A marketing summary is not a substitute for the contract.
For example, The Doctors Company describes its consent protection as subject to policy terms and applicable law. That qualification matters when reviewing any insurer’s settlement language. Source: The Doctors Company coverage overview.
Ask: “If I decline a recommended settlement, does that change the insurer’s payment obligations or my financial responsibility?” Have the agent identify the exact wording rather than answering with a general assurance.
6. Does the quote reflect all of your work?
Give the underwriter a complete description of your activities and ask which are included, excluded, or require an endorsement. Review the proposed named insureds and covered entities carefully.
- Primary specialty and procedures.
- Locum assignments and moonlighting.
- Telehealth services and patient locations.
- Medical-director, supervision, and administrative duties.
- Practice entities, clinicians, and additional locations.
Written clarification is especially useful when you divide time among a private office, hospital shifts, and outside assignments. Describe the actual arrangement; do not rely on a job title to communicate every exposure.
7. What is the total cost of moving forward?
Request a breakdown of the premium and any applicable taxes, fees, installment charges, financing costs, and transition costs. Ask about cancellation terms and whether quoted credits have eligibility conditions.
If tail coverage is needed, evaluate that expense alongside the replacement premium. Also ask whether an early claims-made premium reflects a stage of pricing that may change in later years. A first-year quote is not a promise of future renewal pricing.
What should you do before accepting a quote?
- Resolve the seven comparison questions in writing.
- Confirm that the application accurately describes your work and history.
- Review outstanding underwriting conditions and proposed exclusions.
- Coordinate effective dates and any prior-acts or tail arrangements.
- Obtain written confirmation that coverage has been bound before taking cancellation steps.
A quote is a proposal. Keep the quote, binding confirmation, issued policy, and endorsements together, and check that the issued documents match the terms you accepted.
Frequently asked questions
Is the cheapest malpractice quote the best option?
It may be, but only after comparing coverage terms, covered work, conditions, and total costs. Price alone does not establish that two policies provide comparable protection.
What should I send for a malpractice quote comparison?
Start with your current declarations page, endorsements, renewal quote, and a description of your work. Ask the agent which additional underwriting documents are needed for your situation.
Should I cancel my current policy when I receive a replacement quote?
No. First resolve underwriting conditions, confirm the replacement is bound, and coordinate effective dates and any prior-acts or tail arrangements.
Compare the coverage before choosing the premium
Island Insurance Group can help you review your current policy and evaluate proposed malpractice terms. You can also use the free medical malpractice assessment tool to prepare for an underwriting discussion. An assessment does not bind insurance or guarantee eligibility, pricing, or coverage.
Samuel Bennett, Licensed Insurance Agent
Email: sam@islandinsurancegroup.com
Phone: 954-804-8144
Schedule a 30-minute appointment.
This article provides general insurance education, not legal advice. Coverage, eligibility, premiums, limits, exclusions, and availability depend on the applicant, insurer, and policy terms.