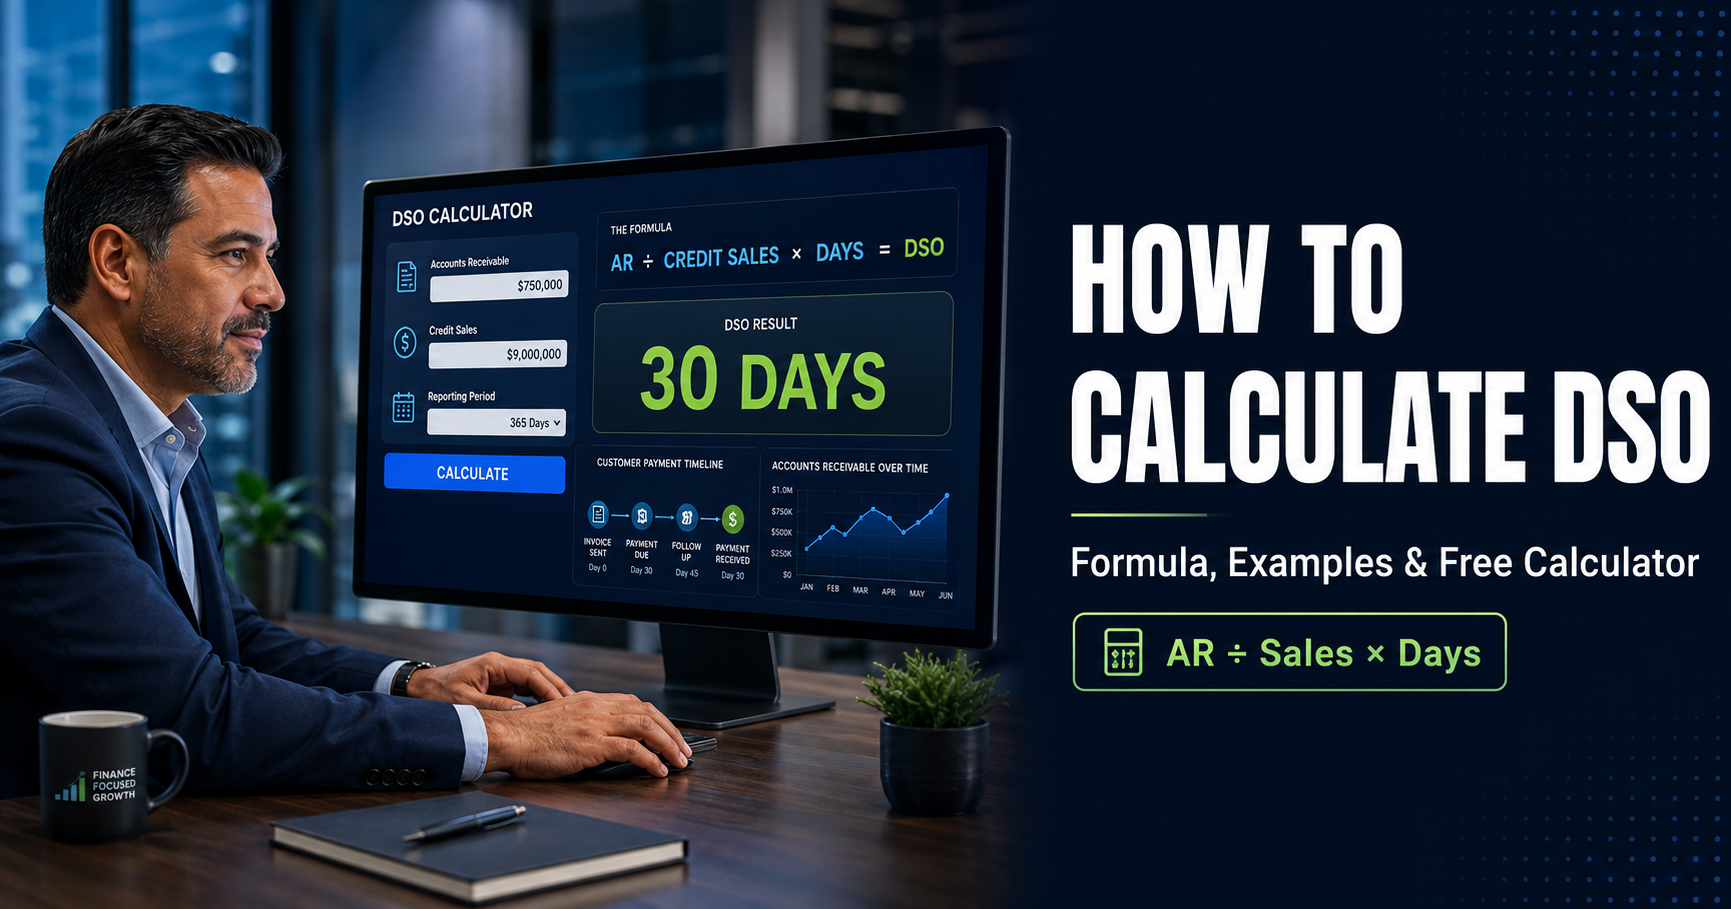
How to Calculate DSO: Formula, Examples & Calculator
Days Sales Outstanding can reveal whether credit sales are turning into cash at the pace your business expects.
The calculation is simple. The difficult part is choosing compatible numbers and interpreting the result correctly.
This guide explains how to calculate DSO, avoid common mistakes and determine what should happen after you have the number.
The DSO formula
Use this formula:
DSO = Accounts Receivable ÷ Total Credit Sales × Number of Days
You need three figures:
- Accounts receivable balance
- Credit sales from the reporting period
- Number of days in that period
All figures should cover the same period.
Step 1: Choose a reporting period
Common reporting periods include:
- 30 or 31 days for a month
- 90 or 91 days for a quarter
- 365 days for a year
Monthly DSO is more responsive to recent changes but may fluctuate. Quarterly DSO can provide a more stable view. Annual DSO may conceal recent deterioration.
Use the same method consistently if you want to compare trends.
Step 2: Find the accounts receivable balance
Locate the accounts receivable balance for the end of the reporting period.
Some organizations use average accounts receivable instead:
Average AR = Beginning AR + Ending AR ÷ 2
Be careful with the order of operations. Write it as:
Average AR = (Beginning AR + Ending AR) ÷ 2
Using average AR can reduce distortion when the ending balance is unusually high or low. Whichever method you choose, apply it consistently.
Step 3: Identify credit sales
Use sales made on credit during the reporting period.
Do not automatically use total revenue. Cash sales do not create accounts receivable and can make DSO appear artificially low.
If credit-sales data is unavailable, any substitute should be clearly documented as an estimate.
Step 4: Apply the formula
Assume a business has:
- Ending accounts receivable: $60,000
- Quarterly credit sales: $180,000
- Reporting period: 90 days
The calculation is:
$60,000 ÷ $180,000 × 90 = 30 days
Estimated DSO is 30 days.
Use the free DSO Calculator to run your own calculation.
Monthly DSO example
Assume a company has:
- Accounts receivable: $45,000
- Monthly credit sales: $90,000
- Reporting period: 30 days
$45,000 ÷ $90,000 × 30 = 15 days
The result is 15 days.
That does not automatically mean every customer pays within 15 days. DSO is an average and may be influenced by payment timing, credit notes and large invoices.
Annual DSO example
Assume a business has:
- Accounts receivable: $400,000
- Annual credit sales: $3,000,000
- Reporting period: 365 days
$400,000 ÷ $3,000,000 × 365 = 48.7 days
The estimated DSO is approximately 49 days.
If customer terms are generally Net 30, the business should investigate why actual collection time appears materially longer.
How should you interpret DSO?
Start by comparing the result with your payment terms.
If average terms are Net 30 and DSO is 45 days, customers are collectively paying later than the contractual due date.
However, do not assume a universal “good” number. Appropriate interpretation depends on:
- Contractual payment terms
- Industry
- Customer type
- Billing frequency
- Seasonality
- Concentration of large accounts
- Reporting method
- Dispute activity
Read What Is a Good DSO? for a more complete interpretation framework.
Common DSO calculation mistakes
Mixing reporting periods
Do not use annual credit sales with a month-end receivable balance and multiply by 30 days.
Including cash sales
Cash sales can understate collection time because they do not create receivables.
Using inconsistent methods
Switching between ending AR and average AR makes trend comparisons less reliable.
Ignoring credit notes and write-offs
Adjustments can affect the receivable balance and should be handled consistently.
Treating DSO as an invoice-level measure
DSO cannot identify which invoice requires attention.
Comparing unrelated businesses
Two businesses with different payment terms, customer types and billing cycles may have valid reasons for different results.
DSO versus an aging report
DSO measures estimated collection speed. An aging report shows where balances are sitting.
A business can have a reasonable DSO while still carrying several severely overdue accounts. Early-paying customers may offset those balances in the average.
Use the Accounts Receivable Aging Calculator alongside DSO for a more complete picture.
What should you do after calculating DSO?
If DSO is stable and consistent with your payment terms:
- Continue monitoring the trend
- Review large and unusual balances
- Maintain the existing follow-up process
If DSO is rising:
- Review invoice timing and accuracy
- Check customer billing contacts
- Analyze aging categories
- Identify disputed invoices
- Review broken payment promises
- Examine recently changed payment terms
- Assign priority accounts for follow-up
Read Why Is My DSO Increasing? before assuming the problem is simply customers refusing to pay.
Connect the calculation to a workflow
A calculator can identify the metric, but the real work occurs at the invoice level.
PaymentPilot helps small businesses organize customer and invoice information, identify priority accounts and review recommended collection actions.
Calculate your Days Sales Outstanding, investigate the accounts driving the result and build a repeatable follow-up process.
Review broader business risks
Use the free Small Business Assessment Tool to examine additional operational and insurance considerations.
You may also schedule a conversation with Samuel Bennett.
Samuel Bennett, Licensed Insurance Agent
sam@islandinsurancegroup.com
954-804-8144
Calculations and interpretations are directional. Consult a qualified accounting or financial professional regarding your business’s records and reporting practices.