Who Controls What Doctors Get Paid? Congress, Insurers and the New Payment Battle
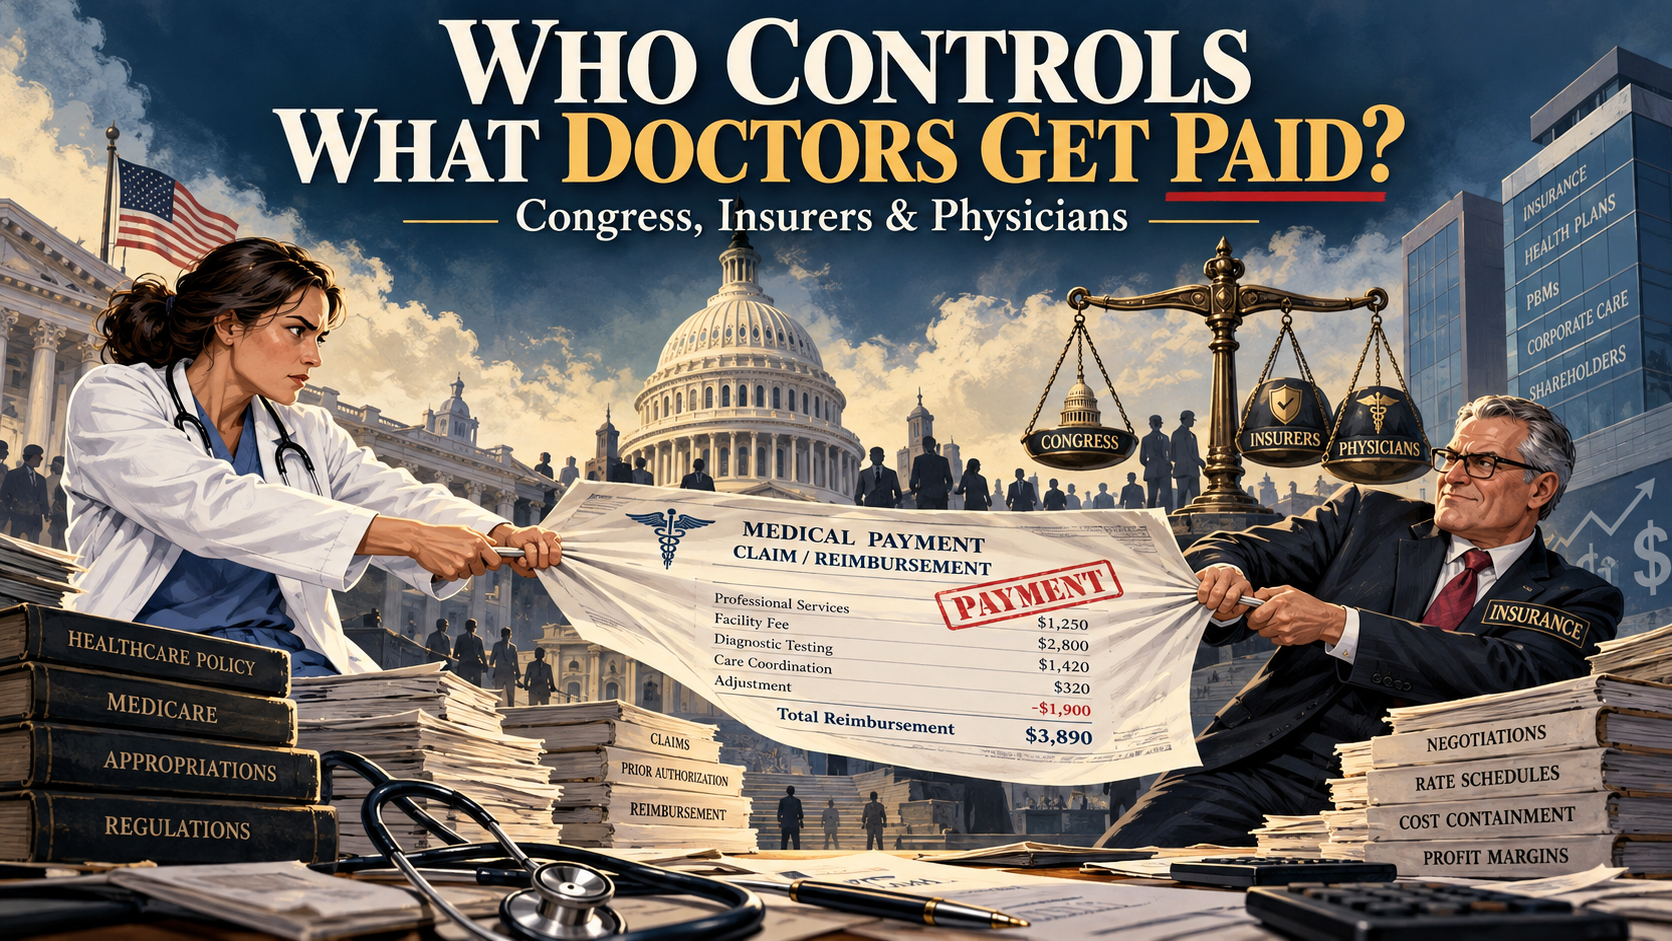
Who Controls What Doctors Get Paid? Congress, Insurers and the New Payment Battle.
A controversial proposal in Congress would eliminate independent arbitration for certain out-of-network medical bills. Supporters promise lower costs and faster payments. Physician groups warn of increased insurer leverage. What’s at stake for independent practices?
Imagine providing emergency medical treatment to a patient, submitting the claim, and then discovering that the reimbursement you receive falls significantly below what you believe the service was worth.
Today, certain qualifying out-of-network disputes can be resolved through an independent federal arbitration process.
But a newly introduced congressional proposal could change that system.
The Lower Premiums, Faster Payments Act (H.R. 10788) , introduced by Rep. Frank Pallone Jr. of New Jersey on October 9, 2026, proposes replacing the federal independent dispute-resolution process for specified services furnished beginning in 2028.
Instead, applicable out-of-network payment amounts would generally be tied to a defined benchmark based on median contracted in-network rates, subject to the bill’s provisions.
Supporters argue that the change could control excessive arbitration costs and speed up physician payments.
Opponents contend that removing independent arbitration would give insurance companies too much influence over reimbursement.
What Is Congress Proposing to Change?
The proposal would amend parts of the No Surprises Act, the federal law designed to protect patients from certain unexpected out-of-network medical bills.
The existing federal system includes an Independent Dispute Resolution process, commonly called IDR.
Under that framework, qualifying healthcare providers and insurers may submit payment disputes to a certified independent entity after required preliminary steps.
The parties submit payment offers, and the decision-maker evaluates those submissions using the statutory and regulatory criteria.
The new proposal would replace that arbitration framework for specified services furnished beginning January 1, 2028.
Instead, the applicable qualifying payment amount, generally derived from median in-network contracted rates and adjusted under relevant rules, would become the payment benchmark.
The bill also contains provisions intended to accelerate payment.
Independent Arbitration
Qualifying disputes may move through a federal IDR process when the parties cannot agree on payment. The arbitrator considers relevant statutory factors when selecting an offer.
Benchmark-Based Payment
Certain affected out-of-network services would instead use a qualifying payment amount benchmark, eliminating the existing arbitration pathway for those services after the proposed transition date.
Why Supporters Say the Current System Needs Reform
Supporters argue that the arbitration process has become more expensive and administratively burdensome than intended.
In an October 8 announcement , Rep. Pallone contended that concentrated use of arbitration by certain provider groups has contributed to costs and payment delays.
His office pointed to approximately 2.5 million disputes submitted in 2025, with a substantial share coming from a relatively small number of groups.
Supporters contend that eliminating the arbitration process could reduce administrative friction and the expense associated with resolving disputes.
They also argue that predictable payment standards could improve timeliness and support efforts to reduce healthcare costs.
Would Patients Actually Pay Lower Premiums?
That is one of the central questions surrounding the legislation.
Reducing payments or administrative costs does not automatically establish how much insurers will reduce premiums, or how quickly any savings would reach patients.
Future outcomes would depend on insurer pricing, provider contracting, implementation, utilization patterns, and other market factors.
Why Physician Organizations Are Opposing the Proposal
The American Society of Anesthesiologists, American College of Emergency Physicians, and American College of Radiology have expressed strong opposition.
In their October 2026 statement , the organizations argued that replacing independent arbitration with insurer-linked payment benchmarks could weaken a safeguard against insufficient reimbursement.
They maintain that independent resolution remains important when physicians and insurers cannot agree on payment.
Those concerns may be especially relevant to specialties where out-of-network services can arise in emergency or facility-based care.
The Concern About Negotiating Power
Physician organizations worry that tying payments to insurer-contracted rates, without the same independent dispute mechanism, could affect future contract negotiations.
Insurers could potentially have stronger incentives to offer lower rates in some circumstances.
However, the actual effect on a particular physician or group would depend on its contracts, service mix, local market, and other factors.
Two Very Different Views of the Same Proposal
The Case for Payment Reform
Supporters believe the current system creates avoidable administrative expenses and can generate unusually high awards.
A predictable benchmark could reduce disputes, improve payment speed, and potentially reduce system-wide costs.
The Case for Independent Review
Opponents argue that independent arbitration is necessary when insurers and providers disagree on appropriate reimbursement.
They worry that eliminating it could shift negotiating leverage and affect certain physician groups.
Both perspectives raise legitimate policy questions: how to protect patients, control unnecessary costs, ensure appropriate physician compensation, and keep essential medical services financially sustainable.
Which Physicians Could Be Most Affected?
The proposal has attracted particular attention from specialties that frequently provide care in hospitals or other facilities where patients may not select every individual clinician.
Anesthesiologists
Certain anesthesia services fall within federal surprise-billing protections. Changes in dispute resolution may affect payment dynamics for qualifying claims.
Emergency Physicians
Emergency services are a major focus of the No Surprises Act. Emergency physician groups are following the proposal closely.
Radiologists
Certain facility-based diagnostic services can involve out-of-network arrangements covered by the federal framework.
Other Physician Groups
Other eligible specialties, facilities, and service arrangements may also be affected, depending on the statutory requirements.
What Does This Mean for Independent Medical Practices?
For independent physician owners, the most important issue may not be the political debate itself.
It may be how changes in reimbursement could influence the financial stability of a practice.
Physician-owned organizations already must manage payroll, staffing, technology, insurance, rent, equipment, and other business obligations.
If reimbursement changes, some practices may need to revisit cash-flow assumptions and contractual arrangements.
That does not mean every independent practice would lose revenue under the proposal.
Instead, practices should assess their actual exposure before making financial decisions based on pending legislation.
Five Questions Physicians Should Ask Before 2027
- How much revenue depends on applicable out-of-network payments? Separate affected claims from other insurance and patient revenue streams.
- What do our payer agreements require? Review reimbursement, termination, dispute resolution, and renegotiation provisions.
- How quickly are claims paid? Evaluate denials, collection delays, appeal costs, and accounts receivable.
- Can the practice absorb payment changes? Model realistic scenarios using actual practice collections and operating expenses.
- Are insurance and financing obligations aligned with the business? Review relevant professional liability, commercial protection, equipment payments, and financing commitments.
Changing Healthcare Economics Require Better Business Planning.
Independent physicians face complicated decisions involving practice growth, financial stability, professional liability, and business protection.
Island Insurance Group provides resources for physicians evaluating malpractice insurance, commercial coverage, and financing referral options for their practices.
Explore Practice Financing Review Malpractice CoverageCould This Legislation Affect Medical Malpractice Insurance?
The Lower Premiums, Faster Payments Act is not itself a proposal to change malpractice insurance coverage, professional liability limits, or state medical negligence laws.
However, a physician’s overall business planning should consider both revenue uncertainty and existing risks.
A practice struggling with reimbursement pressure should not automatically reduce essential insurance without understanding the consequences.
Medical malpractice insurance protects against specified professional liability risks, subject to issued policy terms.
Business owners may also need to evaluate general liability, property, cyber insurance, workers’ compensation, and entity protection as appropriate.
Visit our physician malpractice insurance resources for further guidance.
What Should Physicians Monitor Next?
The proposal is still early in the federal legislative process.
Physicians should monitor committee activity, possible amendments, specialty society communications, and any subsequent legislative developments.
The official H.R. 10788 bill page provides legislative updates.
Practices should avoid treating the proposal as an enacted reimbursement change or making definitive revenue assumptions until the legal framework becomes clearer.
Frequently Asked Questions
What is the Lower Premiums, Faster Payments Act?
H.R. 10788 is a 2026 congressional proposal to revise parts of the No Surprises Act, including replacing the federal independent dispute resolution process for specified services beginning in 2028.
Has Congress passed the Lower Premiums, Faster Payments Act?
No. As of October 26, 2026, the bill had been introduced and referred to House committees. It had not become law.
Would the bill change every doctor’s pay?
No. The legislation addresses specified out-of-network payments under federal surprise-billing rules. It would not uniformly set all physician reimbursement rates.
Why do physician organizations oppose it?
Organizations including the ASA, ACEP, and ACR argue that eliminating independent arbitration could strengthen insurer negotiating leverage and weaken a mechanism used to challenge disputed payments.
Why do supporters favor the proposal?
Supporters argue that the existing arbitration process generates substantial costs and delays and that a benchmark system could improve payment predictability and potentially reduce healthcare expenses.
Would patients pay lower premiums?
That is a stated goal, not a guaranteed result. Actual premium effects would depend on economic, market, and implementation factors.
Does this change Medicare reimbursement?
This proposal concerns specified federal surprise-billing provisions affecting private health insurance, rather than setting Medicare physician fee schedule rates.
The Bottom Line: A Reimbursement Fight With Bigger Implications
The debate over the Lower Premiums, Faster Payments Act illustrates a broader challenge in American healthcare:
How should policymakers balance patient costs, insurance premiums, physician payment, and the sustainability of medical practices?
Supporters see an opportunity to simplify a costly process.
Physician organizations see a risk of concentrating payment decision-making power.
Neither the ultimate legislative outcome nor the financial impact on individual practices has been determined.
For independent physicians, the prudent response is to remain informed, understand payer exposure, monitor potential reimbursement changes, and maintain disciplined financial planning.
Protect the Business Behind Patient Care.
Island Insurance Group works with physicians and healthcare practices evaluating medical malpractice insurance, business protection, and financing resources.
Our goal is to help medical professionals better understand available options while navigating complex business risks.
Explore Our Physician Planning Guide View Healthcare ResourcesSources and Further Reading
U.S. Congress / GovInfo: H.R. 10788 — Official Introduced Bill Text .
House Energy and Commerce Committee Democrats, October 8, 2026: Pallone Introduces Lower Premiums, Faster Payments Act .
American College of Radiology, October 9, 2026: Physician Groups Oppose Changes to Out-of-Network Payments .
Healthcare Finance News, October 9, 2026: Bill Would Overhaul Independent Dispute Resolution .
Becker’s Payer Issues, October 12, 2026: No Surprises Act Author Moves to Replace Arbitration .
Editorial disclosure: This article reflects information available as of October 26, 2026. Legislative proposals may change, fail, or be amended. Discussion of possible economic impacts is not a prediction that any particular insurer or physician will experience a specific financial outcome.
Insurance and legal notice: This material is for general educational purposes and does not constitute legal, regulatory, financial, or insurance coverage advice. Coverage depends on actual policy terms, underwriting, limits, exclusions, and eligibility. Financing resources are subject to participating providers’ terms and approvals.