General Liability Insurance for Small Businesses: Coverage, Costs and Gaps
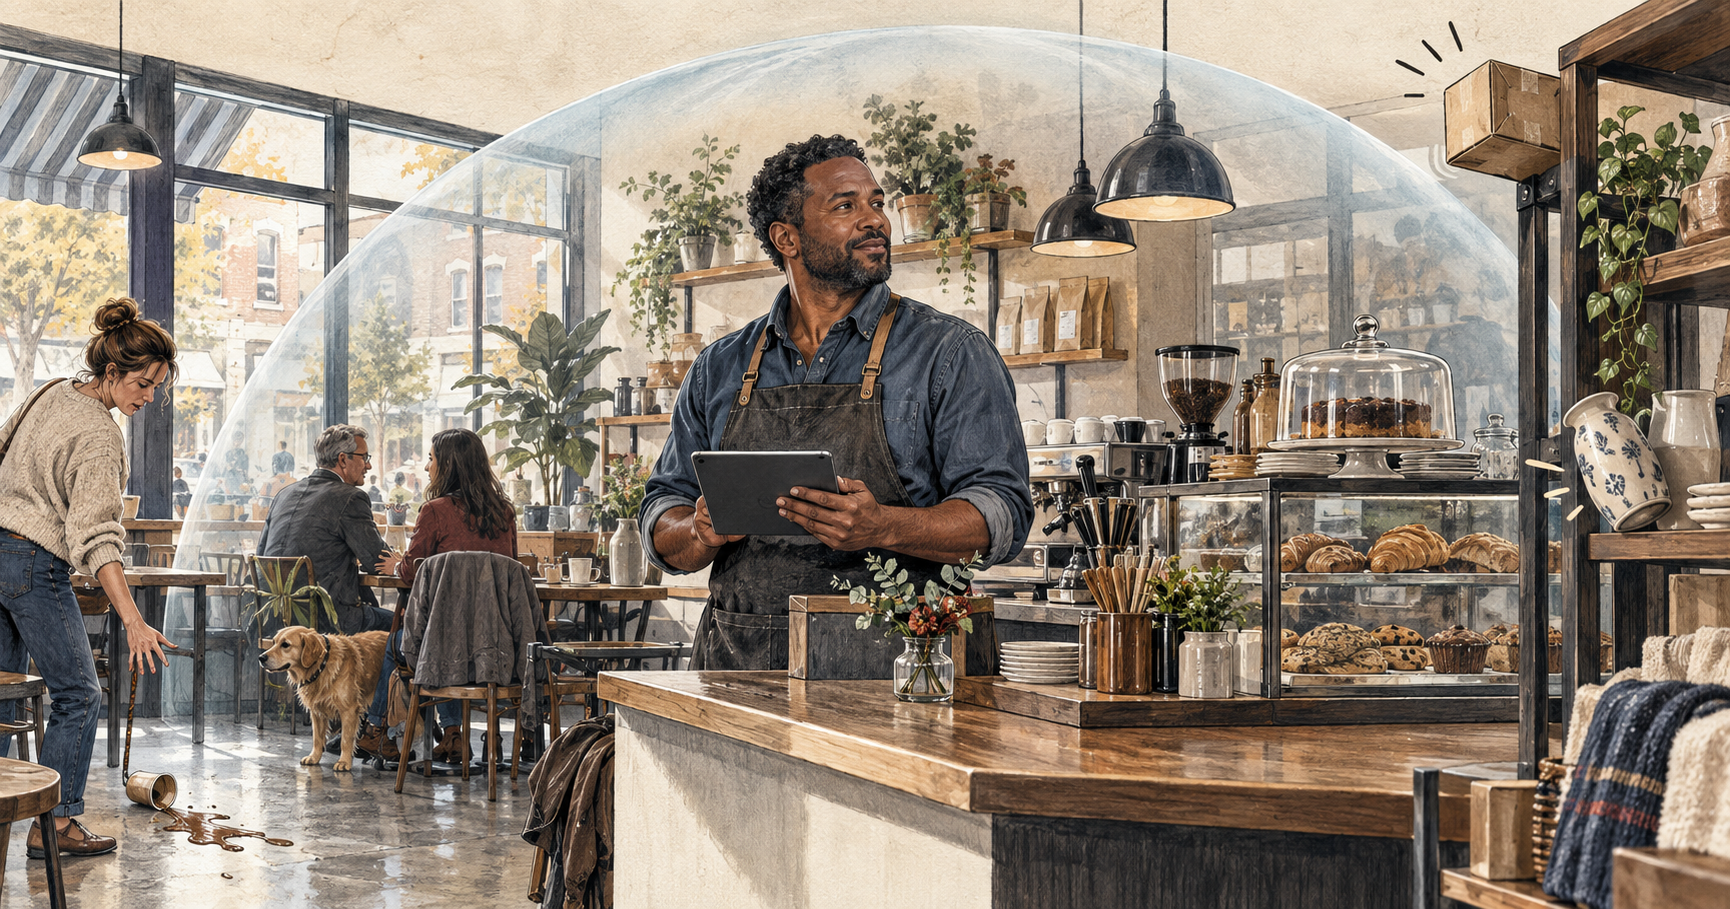
A customer slips in your office. An employee accidentally damages a client’s property. A competitor claims that one of your advertisements harmed its reputation.
Each situation can create legal expenses and financial pressure for a small business.
Commercial general liability insurance is designed to address many common third-party claims. It is a foundational business policy, but it is not a universal shield.
Understanding what general liability covers—and what it leaves out—is essential before relying on it to protect your business.
What Is General Liability Insurance?
General liability insurance helps protect a business from certain claims involving third-party bodily injury, third-party property damage and personal or advertising injury.
Depending on the policy and circumstances, coverage may include legal defense expenses and covered settlements or judgments.
The U.S. Small Business Administration describes general liability insurance as protection against financial losses involving bodily injury, property damage, medical expenses, libel, slander and lawsuit defense, subject to the insurance policy.
General liability can be purchased as a standalone policy or included in a business owner’s policy, commonly known as a BOP.
What Does General Liability Insurance Cover?
Although policies differ, common coverage areas include the following.
Third-Party Bodily Injury
If a customer, vendor or visitor is injured because of an alleged hazard connected to your business, the policy may help pay covered defense expenses and damages.
Example: A delivery person trips over an unsecured electrical cable in your office and suffers an injury.
Third-Party Property Damage
Coverage may respond when your business becomes legally responsible for damaging property belonging to someone else.
Example: An employee performing work at a customer’s location accidentally damages the customer’s flooring.
Personal and Advertising Injury
This portion may cover specified offenses such as libel, slander and certain advertising-related injuries.
It does not make every advertising or intellectual-property dispute insurable. The policy’s definitions and exclusions must be reviewed.
Medical Payments
A general liability policy may provide a limited amount for medical expenses arising from certain injuries, sometimes without requiring a determination of fault.
Legal Defense
Even an allegation that is ultimately dismissed can produce substantial attorney fees, court costs and investigation expenses.
A general liability policy may pay the defense costs associated with a covered lawsuit. Whether those expenses reduce the available liability limit depends on the policy.
What General Liability Insurance Usually Does Not Cover
One of the biggest insurance mistakes a small-business owner can make is assuming general liability covers every possible claim.
It generally does not replace:
- Professional liability or errors-and-omissions insurance
- Workers’ compensation insurance
- Commercial auto insurance
- Cyber insurance
- Employment practices liability insurance
- Commercial property insurance
- Directors and officers liability insurance
- Crime or social-engineering coverage
For example, a consultant accused of providing negligent professional advice may need errors-and-omissions coverage. A company affected by ransomware may need cyber insurance. A business whose equipment is damaged may need commercial property coverage.
General liability also contains exclusions, conditions and limitations. A certificate of insurance is evidence that coverage exists; it is not a substitute for reviewing the policy.
Does Every Small Business Need General Liability Insurance?
General liability insurance is not legally required for every business in every location. However, it is frequently required by contract.
A landlord, client, property manager, general contractor or vendor may require a business to maintain specified limits and provide additional-insured status before work begins.
Even without a contractual requirement, general liability deserves consideration if your business:
- Receives customers or visitors
- Works at client locations
- Leases commercial space
- Handles customer property
- Uses advertising or social media
- Participates in events or trade shows
- Signs contracts containing indemnification clauses
- Uses subcontractors
- Sells or distributes products
The real question is not simply whether insurance is mandatory. It is whether the business could comfortably absorb the cost of defending and resolving a claim without insurance.
How Much Does General Liability Insurance Cost?
There is no responsible one-price answer.
The cost of general liability insurance can depend on:
- Industry and business operations
- Annual revenue
- Payroll and employee count
- Business location
- Customer foot traffic
- Subcontractor use
- Claims history
- Requested liability limits
- Deductible
- Products or completed-operations exposure
- Additional-insured requirements
- Coverage endorsements
A consultant working from home presents a different risk from a contractor operating at multiple customer locations.
Quotes should be based on an accurate description of the business. Using an incomplete or incorrect classification to obtain a lower premium can create serious problems if a claim occurs.
Understanding General Liability Limits
A general liability policy commonly includes a per-occurrence limit and a general aggregate limit.
For example, a policy may provide $1 million per occurrence and a $2 million general aggregate.
Per-Occurrence Limit
The per-occurrence limit is the most the policy will pay for a covered occurrence, subject to all policy terms and sublimits.
General Aggregate Limit
The general aggregate is the maximum available for specified covered claims during the policy period.
Products-Completed Operations Aggregate
This is a separate aggregate that may apply to eligible claims involving products or completed work.
Medical Expense Limit
This is a smaller sublimit that may apply to eligible medical-payment expenses.
Contractual requirements may determine the minimum limits a business must carry. Businesses with more severe exposures may require higher limits or an umbrella policy.
An umbrella or excess liability policy can provide additional limits over scheduled underlying policies. However, it does not automatically eliminate every exclusion in the underlying coverage.
General Liability vs. a Business Owner’s Policy
General liability primarily addresses liability claims made by third parties.
A business owner’s policy usually combines general liability with commercial property insurance and, in many cases, business-income protection.
A BOP may be efficient for an eligible small business that needs both liability and property protection.
A standalone general liability policy may make more sense when the business has limited property exposure, requires specialized coverage or does not qualify for a standard BOP.
General Liability vs. Professional Liability
General liability and professional liability address different risks.
General liability commonly responds to claims involving bodily injury, property damage and specified personal or advertising injuries.
Professional liability generally responds to allegations that a business made an error, failed to perform a professional service or provided negligent advice.
Some businesses need both.
For example, an IT consultant could face a general liability claim if an employee damages a customer’s office. The same consultant could face a professional liability claim if a software error allegedly causes the customer a financial loss.
Seven Questions to Ask Before Buying Coverage
Before purchasing or renewing a general liability policy, ask:
- Are all business operations and revenue sources disclosed?
- Are subcontractors and independent contractors addressed properly?
- Do any contracts require additional-insured endorsements?
- Are defense expenses inside or outside the liability limits?
- Does the policy include products and completed operations?
- Which professional, cyber, auto and employment exposures are excluded?
- Are the correct legal entity, DBA and locations listed?
The lowest premium does not necessarily represent the best value. A policy should accurately reflect how the company operates.
Identify Your Business Risk Exposures
Before requesting a quote, use the Bennett Risk Intelligence diagnostic to uncover operational exposures, contractual concerns and potential coverage areas that may need closer review.
For help evaluating your existing coverage or comparing business-insurance options, visit Island Insurance Group.
You can also schedule a 30-minute conversation or contact:
Samuel Bennett
Licensed Insurance Agent
Email: sam@islandinsurancegroup.com
Phone: 1-866-820-7430
Frequently Asked Questions
Is general liability insurance required by law?
Requirements vary by location and industry. Even when general liability is not legally mandated, landlords and clients may require it by contract.
Does general liability cover mistakes in professional services?
Usually not. Allegations involving errors in professional advice or services are commonly addressed by professional liability or errors-and-omissions insurance.
Does forming an LLC eliminate the need for liability insurance?
No. An LLC and an insurance policy serve different purposes. A lawsuit can still create defense expenses and liabilities for the business.
Can I add a client as an additional insured?
Often, when the request is appropriate and approved by the carrier. The required endorsement should match the contract and business relationship. Merely placing a client’s name on a certificate may not create additional-insured status.
Does general liability insurance cover a data breach?
General liability usually does not provide adequate protection for a data breach. Businesses should assess cyber insurance for privacy liability, breach response, ransomware and related exposures.
This article provides general insurance information and is not legal advice. Coverage depends on the policy language, endorsements, exclusions and facts surrounding a claim. Availability and requirements vary by carrier and jurisdiction.